In extreme markets, disciplined rebalancing is a risk management protocol, not a market-timing guess.
- Winning positions, if left unchecked, covertly transform a balanced portfolio into a concentrated, high-risk bet.
- Emotional biases, like the « house money effect, » are the primary obstacle to rational decision-making during market euphoria.
Recommendation: Create a formal Investment Policy Statement (IPS) with pre-defined rebalancing thresholds to automate your strategy and enforce discipline before emotions take over.
When markets reach extreme valuations, a disciplined investor faces a critical challenge. The portfolio is likely showing significant gains, particularly in the asset classes driving the rally. The common emotional response is euphoria, a desire to let winners run indefinitely. The common fear is missing out on further gains by trimming positions too early. This environment is precisely where a systematic, unemotional approach to portfolio management proves its worth. The goal is not to perfectly time the market peak—an impossible task—but to systematically manage risk and adhere to a long-term strategic allocation that was established during a calmer, more rational period.
Most advice boils down to simplistic platitudes like « sell high, buy low. » While true, this offers no practical guidance. The real challenge lies in execution: having a pre-defined, non-negotiable process that triggers automatically, removing the flawed human element of fear and greed from the equation. This article will not rehash generic advice. Instead, it will provide a disciplined framework for rebalancing when valuations become detached from historical norms. We will treat the portfolio not as a collection of lottery tickets, but as an engineered system designed to achieve a specific risk-adjusted return over the long term. This system requires periodic maintenance, especially when under the stress of market extremes.
This guide will detail the mechanics of a threshold-based strategy, explore the psychological traps that prevent rational action, and outline a process for reallocating capital efficiently. We will establish how to build a robust, automated strategy that protects capital and maintains the integrity of your original investment plan, regardless of market froth.
This article provides a structured path to mastering portfolio rebalancing in volatile times. The following sections break down the core components of a disciplined strategy, from execution mechanics to psychological defense.
Summary: A Systematic Guide to Rebalancing in Extreme Markets
- How to Execute a Threshold Rebalancing Strategy to Sell High and Buy Low?
- Why Letting Winning Stocks Run Unchecked Radically Alters Your Risk Profile?
- How to Reallocate Capital From Overvalued Tech to Undervalued Value Sectors?
- The Psychological Trap of Refusing to Trim Stocks That Have Doubled in Price
- When to Perform Your Annual Portfolio Overhaul for Maximum Tax Efficiency?
- When to Rebalance Your Assets During Major Economic Shifts?
- When to Review Your Automated Strategy Without Disrupting Long-Term Goals?
- How to Automate Your Investment Strategy and Eliminate Costly Emotional Decisions?
How to Execute a Threshold Rebalancing Strategy to Sell High and Buy Low?
A threshold rebalancing strategy is a systematic protocol for maintaining a portfolio’s target asset allocation. Unlike calendar-based rebalancing (e.g., annually or quarterly), this method triggers trades only when an asset class deviates from its target by a pre-determined percentage, such as 5% or 10%. This approach is inherently more responsive to market dynamics, forcing the investor to systematically sell assets that have performed exceptionally well (selling high) and buy assets that have underperformed (buying low) to return to the desired risk posture. The key is defining the rules of the system in advance, removing any need for emotional judgment in the heat of the moment.
The execution begins with setting clear, non-negotiable thresholds for each major asset class in your portfolio. For a 60/40 stock/bond portfolio with a 5% threshold, rebalancing would be triggered if stocks grew to represent 65% of the portfolio or fell to 55%. The choice of threshold depends on the volatility of the assets and the investor’s tolerance for transaction costs. A wider band (e.g., 10%) results in less frequent trading but allows for more significant deviation, while a narrower band maintains tighter control at the expense of potentially higher costs and taxes. Research confirms the primary benefit is risk reduction; a 15-year study shows all rebalancing frequencies achieve similar volatility reduction, while a hands-off approach results in significantly higher risk.
During periods of extreme valuation, it can be prudent to layer valuation metrics on top of simple percentage thresholds. For example, a rule might state: « Rebalance only when an asset class exceeds its threshold AND its sector-wide valuation (e.g., P/E ratio) is more than 25% above its 10-year historical average. » This adds a layer of sophistication, creating a « valuation-aware threshold » that focuses rebalancing efforts on the most over-extended parts of the market. This turns a simple mechanical rule into an intelligent, systematic protocol.
Ultimately, the specific percentage is less important than the discipline to execute the pre-defined plan without hesitation. This mechanical process is the core of removing emotion and maintaining your portfolio’s intended risk profile.
Why Letting Winning Stocks Run Unchecked Radically Alters Your Risk Profile?
The most insidious danger in a bull market is « risk creep »—the silent, gradual transformation of a diversified portfolio into a concentrated, high-risk bet. This happens without any active decision from the investor. As a single asset class, like technology stocks, dramatically outperforms, it naturally consumes a larger and larger percentage of the total portfolio value. A portfolio that began as a balanced 60% stock and 40% bond allocation can easily morph into an aggressive 80% or even 90% stock allocation. While the account balance looks wonderful, the underlying risk profile integrity has been compromised. The investor is now exposed to far more downside risk than they originally intended or are comfortable with.
This phenomenon is best understood with a simple example. Consider an investor who starts with a $10,000 portfolio allocated 60/40 to stocks and bonds. If the stock portion doubles in value while bonds remain flat, the portfolio is now worth $16,000. However, the stock allocation is now $12,000 and bonds are $4,000. This is no longer a 60/40 portfolio; it has become a 75/25 portfolio. The investor who chose a moderate risk profile is now unknowingly managing a growth-oriented, higher-risk one. A future 20% drop in the stock market would now cause a $2,400 loss, whereas in the original 60/40 portfolio, it would have been a more manageable $1,200 loss. The portfolio’s volatility and potential for large drawdowns have increased substantially.
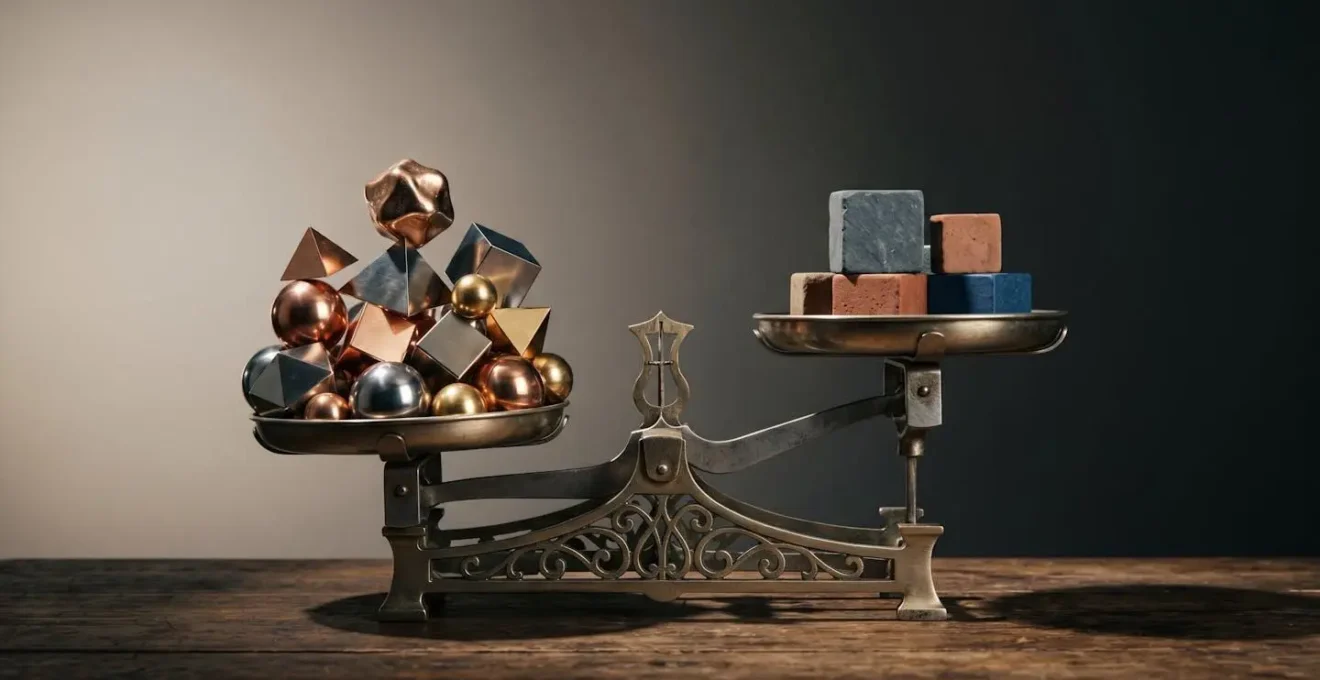
This visual metaphor of imbalance is critical. As one side becomes heavier, the entire structure becomes less stable and more susceptible to a catastrophic break. Systematic rebalancing acts as the corrective force, trimming the overweight side and adding to the underweight side to restore equilibrium. It is a fundamental act of risk management. Failing to rebalance is not a passive strategy; it is an active decision to accept a new, higher-risk profile that you did not consciously choose.
Letting winners run feels good, but it is an abdication of disciplined portfolio management. It substitutes a long-term strategy for short-term momentum chasing, a path that rarely ends well.
How to Reallocate Capital From Overvalued Tech to Undervalued Value Sectors?
Once a rebalancing trigger is hit, the next step is the mechanical process of reallocation. This involves selling a portion of the over-performing asset class and using the proceeds to purchase the under-performing one. When markets are at extremes, this often means trimming exposure to high-growth sectors like technology and reallocating that capital to historically undervalued sectors, such as financials, industrials, or energy. The process must be executed with the same systematic discipline as the decision to rebalance. It is not about making a bearish call on technology, but about restoring the portfolio to its strategic target weights.
The first consideration is tax efficiency. Whenever possible, rebalancing should be done within tax-advantaged accounts like a 401(k) or an IRA. Since there are no capital gains taxes on trades within these accounts, you can sell and buy freely to restore your target allocation without a tax penalty. If rebalancing must occur in a taxable brokerage account, the focus shifts to minimizing the tax impact. This can involve tax-loss harvesting—selling other positions at a loss to offset the gains from the profitable positions you are trimming. Additionally, you can use specific lot identification (if your broker supports it) to sell the shares you purchased at the highest cost first, thereby reducing your realized capital gain.
The choice of rebalancing methodology directly impacts how and when you reallocate. A systematic comparison reveals the trade-offs between different protocols.
A recent comparative analysis of rebalancing strategies provides a clear framework for investors.
| Approach | Frequency | Pros | Cons | Best For |
|---|---|---|---|---|
| Calendar-Based | Quarterly/Annually | Simple to implement, predictable schedule | May miss significant drifts between intervals | Passive investors |
| Threshold-Based | When 5-10% deviation occurs | Responds to actual portfolio changes | Requires constant monitoring | Active investors |
| Hybrid Approach | Calendar review + threshold trigger | Balances simplicity with responsiveness | More complex to manage | Sophisticated investors |
The destination for the reallocated capital should also be pre-defined. If your strategy dictates a 20% allocation to international stocks and they have fallen to 15%, the proceeds from trimming domestic growth stocks should be directed there. The entire process is a rule-based execution of your long-term plan.
The Psychological Trap of Refusing to Trim Stocks That Have Doubled in Price
The single greatest barrier to successful rebalancing is not financial, but psychological. When an investment has performed exceptionally well, a host of cognitive biases conspire to prevent us from taking the rational step of trimming the position. One of the most powerful is the « house money effect, » a bias where investors treat profits differently than their initial capital. They become more willing to take risks with their « winnings, » viewing it as free money. This leads to the dangerous belief that letting a hyper-inflated position ride is a « no-risk » proposition, ignoring the reality that a 50% gain followed by a 50% loss results in a 25% net loss of that capital.
As described in a case study on investor behavior, this cognitive bias causes investors to let winning positions grow unchecked. An investor who sees their tech stocks double might resist trimming because they view the gains as ‘house money,’ ignoring that a 50% position in one sector exposes them to catastrophic risk if that sector corrects. This is compounded by endowment bias (overvaluing something we own) and the fear of missing out (FOMO) on even more potential gains. The brain frames trimming a winner as « losing » future profits, rather than as « locking in » current gains and managing risk.
To overcome this, a disciplined investor needs a « behavioral circuit breaker. » A simple but powerful mental tool is the « Stranger Test. »
As posed by The Stranger Test for Portfolio Rebalancing, the key question to ask is simple:
If I had this position’s value in cash today, would I buy the stock at its current price?
– Common Investor Psychology Test, The Stranger Test for Portfolio Rebalancing
If the answer is no, it is a clear signal that you are only holding the oversized position due to inertia and emotional attachment, not because of a rational belief in its future risk-adjusted returns. The only logical action is to trim the position back to its strategic target weight. A pre-defined, automated rebalancing strategy is the ultimate circuit breaker, as it forces you to act based on rules, not on the fleeting and often-flawed emotions of the moment.
Without a system to enforce discipline, even the most intelligent investors can fall victim to their own psychology, turning a winning strategy into a portfolio-destroying mistake.
When to Perform Your Annual Portfolio Overhaul for Maximum Tax Efficiency?
While threshold-based rebalancing responds to market movements, a scheduled annual review remains a critical component of a disciplined strategy, primarily for tax optimization. Performing a portfolio overhaul at a specific time of year allows you to strategically manage capital gains and losses. The ideal time for this review is typically late November or early December. This provides enough time before year-end to identify and execute trades for maximum tax efficiency without being rushed.
The primary goal of this year-end review is tax-loss harvesting. This involves intentionally selling investments in your taxable account that have an unrealized loss. These realized losses can then be used to offset any capital gains you’ve realized during the year, including gains from rebalancing over-performing assets. If your losses exceed your gains, you can use up to $3,000 of the excess loss to offset your ordinary income, with any remaining losses carried forward to future years. This is a powerful tool for reducing your tax bill. Conversely, investors in a 0% long-term capital gains tax bracket might consider « tax-gain harvesting »—intentionally selling appreciated assets to realize gains tax-free and then immediately repurchasing them to reset their cost basis to a higher level.
It’s important to remember that tax efficiency should serve the investment strategy, not the other way around. Frequent rebalancing, especially during volatile periods, can lead to unintended consequences. As noted in market analysis, high volatility periods can trigger multiple taxable events with a strict threshold-based system. Therefore, the annual review is the perfect time to reconcile your rebalancing activities with your tax strategy, ensuring they work in harmony. Using tax-advantaged accounts for the majority of rebalancing trades remains the simplest and most effective strategy.
Your Checklist for Tax-Efficient Annual Rebalancing
- Review in early December for tax-loss harvesting opportunities before year-end.
- Identify positions with losses to offset realized gains from rebalancing.
- For those in 0% capital gains bracket, consider tax-gain harvesting to reset cost basis.
- Use Specific Lot Identification to sell highest cost basis shares first.
- Execute rebalancing trades in tax-advantaged accounts (401k, IRA) when possible.
- If over 73, coordinate rebalancing with Required Minimum Distributions.
This annual overhaul ensures that your portfolio remains aligned with your long-term goals not just in its asset allocation, but also in its tax-efficient structure.
When to Rebalance Your Assets During Major Economic Shifts?
Strategic rebalancing, based on fixed thresholds, should be the default operating procedure for a long-term investor. However, major economic shifts—such as the beginning of a recession, a change in monetary policy from the central bank, or a major geopolitical event—can warrant a tactical review. This does not mean abandoning the long-term strategy, but rather considering whether the underlying assumptions of that strategy are still valid. A tactical rebalancing approach involves a temporary, deliberate deviation from the strategic allocation to capitalize on or protect against a specific, forecasted market condition.
For instance, if leading economic indicators like an inverted yield curve or a sharply declining ISM Manufacturing Index strongly signal a coming recession, a disciplined investor might tactically shift their allocation. This could involve pre-emptively trimming equities even before a rebalancing threshold is hit and increasing allocation to defensive assets like long-term government bonds or gold. This is a high-level maneuver that should be used sparingly and with a clear thesis. The key is to have pre-defined signals for both entering and, just as importantly, exiting the tactical allocation and returning to the strategic baseline. Without an exit plan, a tactical shift can easily become a permanent, and often misguided, new strategy.
During these periods of extreme uncertainty, maintaining a healthy cash position becomes a strategic asset. Many financial advisors recommend maintaining a 5-20% ‘dry powder’ cash allocation. This cash serves two purposes: it acts as a buffer, dampening portfolio volatility during a downturn, and it provides the liquidity needed to take advantage of buying opportunities when other investors are panic-selling. This « dry powder » is not idle money; it is a tactical tool waiting to be deployed as part of a disciplined rebalancing strategy when asset prices become disconnected from their fundamental value.
Ultimately, any tactical shift should be a rare exception to the rule of consistent, strategic rebalancing. For the vast majority of the time, the automated, threshold-based system is the most reliable path to long-term success.
When to Review Your Automated Strategy Without Disrupting Long-Term Goals?
Once you have an automated investment and rebalancing strategy in place, the temptation can be to either constantly tinker with it or to forget it entirely. Both are mistakes. The purpose of automation is to enforce discipline and remove emotion, but it is not a « set and forget forever » solution. Your automated strategy requires periodic, scheduled reviews to ensure it remains aligned with your life and financial goals. The key is to conduct these reviews in a structured way that prevents impulsive changes based on short-term market noise.
The best practice is to schedule a review once a year, on a fixed date that is emotionally neutral, such as your birthday or the anniversary of opening the account. This annual review is not the time to second-guess the strategy because of recent market performance. Instead, it is a time to ask if your personal circumstances have changed in a way that fundamentally alters the strategy’s core assumptions. The goal is to verify that the automated system is still working towards the right objectives.
A structured review protocol should focus on your personal situation, not the market. Key questions to document and answer annually include:
- Risk Tolerance: Has my willingness or ability to take financial risk materially changed?
- Time Horizon: Has my retirement date or the timeline for a major goal (e.g., college fund, house purchase) shifted significantly?
- Financial Goals: Are the objectives I am saving for still the same? Have any new goals emerged?
- Life Changes: Have I experienced a major life event, such as marriage, the birth of a child, a significant job change, or an inheritance, that impacts my financial picture?
Only a significant change in the answer to one of these questions should warrant a potential adjustment to the automated strategy’s target allocation or savings rate. Overriding the automation for any other reason—especially in response to market volatility—defeats its entire purpose.
The review is a check-up on the pilot (you), not a redesign of the airplane (the strategy) while it is in flight. It reinforces the system’s role as the guardian of your long-term goals.
Key takeaways
- Rebalancing is a risk management tool, not a market-timing tool. Its primary function is to return your portfolio to its intended risk profile.
- A pre-defined system, whether based on thresholds or codified in an Investment Policy Statement (IPS), is your best defense against emotional decision-making in extreme markets.
- Tax efficiency is not an afterthought; it must be integrated into your rebalancing process, primarily by prioritizing trades within tax-advantaged accounts.
How to Automate Your Investment Strategy and Eliminate Costly Emotional Decisions?
The logical endpoint of a systematic investment approach is automation. By building a system that executes your investment and rebalancing plan without your direct intervention, you effectively eliminate the greatest threat to long-term returns: your own emotional impulses. Automation can range from simple, periodic contributions to a fully managed robo-advisory account. The right level depends on the investor’s desire for control, technical comfort, and willingness to pay for convenience. The goal remains the same across all levels: to make disciplined, rational investing the default, easy choice.
A powerful tool to guide this automation is the creation of a personal Investment Policy Statement (IPS). An IPS is a written document that acts as a constitution for your portfolio. As highlighted by the investment community at Bogleheads.org, which champions disciplined investing, this pre-commitment contract enforces discipline during market turmoil. The IPS formally outlines your financial goals, risk tolerance, target asset allocation, and, crucially, your specific rules for rebalancing. By codifying that you will rebalance when an asset class drifts by 5%, you are making a promise to your future self—a promise that is much harder to break when faced with the emotional stress of a market bubble or crash.
Different levels of automation can be implemented to enforce the rules laid out in your IPS. Each level offers a different trade-off between control, cost, and convenience.
| Automation Level | Tools Required | Investor Involvement | Cost Range | Best For |
|---|---|---|---|---|
| Full Automation (Robo-Advisors) | Wealthfront, Betterment | Minimal – set and forget | 0.25-0.50% annually | Beginners, busy professionals |
| Hybrid Automation | Brokerage auto-invest, alerts | Moderate – quarterly review | $0-50/year in fees | DIY investors wanting some control |
| Rule-Based Manual | Spreadsheet, calendar reminders | High – active management | Trading costs only | Experienced active investors |
Ultimately, automating your strategy is the highest form of disciplined investing. It is the final step in transitioning from an emotional market participant to a systematic, unemotional owner of a well-oiled investment machine. The most logical next step for any disciplined investor is to formalize their strategy by drafting a personal Investment Policy Statement.