In summary:
- Market timing is a losing game; consistency through pound-cost averaging statistically wins over the long term.
- True automation is a behavioural defence system, not just a convenience, designed to short-circuit emotional reactions like panic-selling.
- Set up automated Direct Debits into your ISA or SIPP for the day after your payday to make investing non-negotiable.
- Review your core strategy only during major life events, not market volatility, to protect your long-term goals.
- Create a « Wealth Flywheel » by automating salary sweeps, investments, rebalancing, and annual contribution increases to guarantee consistent wealth accumulation.
The feeling is all too common for UK investors: a sudden market downturn flashes red across your portfolio, and an immediate, visceral urge to « do something » takes over. This instinct, often leading to panic-selling, is the single most destructive force in wealth creation. Many advisors suggest simply « staying the course » or « investing for the long term, » but this advice crumbles precisely when our emotional responses are at their peak. These generic platitudes fail to provide a robust mechanism to protect us from our own worst instincts.
The conventional view of investment automation is one of convenience—a simple « set-and-forget » tool. But what if its true purpose is far more profound? What if automation is not about making investing easier, but about building a behavioural fortress? The real key to long-term success isn’t trying to outsmart the market or even control your emotions, but to build a systematic framework that makes your emotional reactions irrelevant to your financial outcomes. By creating rules-based processes, you actively design a system that bypasses the cognitive biases that lead to costly mistakes.
This guide will deconstruct the process of building that fortress. We will explore why systematic, automated investing consistently outperforms discretionary, emotional trading. We will provide a step-by-step method for setting up automated salary sweeps into your ISA, differentiate between productive strategy reviews and destructive tinkering, and ultimately show you how to construct a complete financial automation flywheel that guarantees consistent, dispassionate wealth accumulation.
This article provides a structured methodology to move from reactive decision-making to a proactive, automated system. The following sections break down each critical component of this disciplined approach, offering a clear roadmap to secure your financial future.
Summary: A Disciplined Framework for Automated Wealth Creation
- Why Market Timing Strategies Consistently Underperform Pound-Cost Averaging?
- How to Set Up a Direct Debit Investment Plan That Ignores Financial News?
- When to Review Your Automated Strategy Without Disrupting Long-Term Goals?
- The Discretionary Trading Illusion That Derails Carefully Planned Portfolios
- Lump-Sum Investing vs Monthly Drip-Feeding: Which Reduces Your Psychological Stress?
- How to Automate Your Salary Sweeps to Fund Your ISA on Payday?
- Why Delaying Your Investment Journey by 5 Years Costs You £200,000?
- How to Automate Your Finances to Guarantee Consistent Wealth Accumulation?
Why Market Timing Strategies Consistently Underperform Pound-Cost Averaging?
The allure of market timing—selling before a crash and buying at the bottom—is powerful, but it’s a statistically proven path to underperformance. The core problem is that the market’s best days often occur in shocking proximity to its worst. This clustering makes successfully navigating in and out of positions nearly impossible. As analysis from JP Morgan Asset Management highlights, « Seven of the 10 highest-returning market days over the past 20 years happened within two weeks of the market’s largest one-day declines. » Attempting to sidestep the downturns almost guarantees you will also miss the sharp, powerful rebounds that follow.
The financial cost of this flawed strategy is staggering. Missing just a handful of these crucial recovery days can decimate long-term returns. According to extensive Hartford Funds research, a 54% reduction in returns is the penalty for an investor who missed the 10 best days of the market over a 30-year period. Further data reinforces this, showing that over a similar timeframe, missing the 30 best days could drag an average annual return of 8.4% down to just 2.1%, which is below the historical rate of inflation. In essence, trying to be clever with market timing often results in going backward in real terms.
This is where pound-cost averaging, the cornerstone of automated investing, proves its superiority. By investing a fixed amount of money at regular intervals, you automatically buy more shares when prices are low and fewer when they are high. This removes the impossible task of prediction from the equation. It imposes a mechanical discipline that is immune to fear and greed. Instead of guessing the market’s next move, you leverage its volatility over time, turning short-term fluctuations from a source of stress into a long-term advantage.
How to Set Up a Direct Debit Investment Plan That Ignores Financial News?
The most effective way to implement pound-cost averaging and ignore market noise is to build a system of « systematic apathy. » This is achieved by setting up an automated investment plan via Direct Debit, a simple but powerful tool for enforcing discipline. The goal is to make your investment contributions as regular and non-negotiable as a mortgage payment or utility bill. By automating the process, you remove the moment of decision—and therefore, the moment of temptation to waiver based on a scary headline or a volatile day.
Building this automated system is a straightforward, technical process. The key is to schedule the investment to occur before you have a chance to second-guess it. For most people, this means setting the Direct Debit to transfer funds from a current account into an investment vehicle like a Stocks and Shares ISA or a SIPP on the day after their salary is paid. This « pay yourself first » approach ensures your long-term goals are prioritised over discretionary spending.
As this visualisation suggests, the process should be a recurring, almost mundane, part of your financial calendar. Here’s a simple framework to set it up:
- Choose Your Platform: Select a low-cost investment platform or robo-advisor in the UK that allows for automated, recurring investments.
- Select Your Investments: Decide on a diversified portfolio that matches your risk tolerance and long-term goals. A global index tracker fund or a target-date fund are common starting points for a « set-and-forget » strategy.
- Determine Your Amount: Realistically assess how much you can comfortably invest each month without straining your finances. Even small, consistent amounts can grow substantially over time due to compounding.
- Set Up the Direct Debit: Log in to your investment platform and link your bank account. Create a recurring investment instruction for a fixed amount to be invested on a specific day each month, ideally the day after you get paid.
When to Review Your Automated Strategy Without Disrupting Long-Term Goals?
An automated strategy is not a « fire-and-forget » missile; it’s more like a commercial airliner on autopilot. While it handles the moment-to-moment adjustments, a pilot is still needed to ensure it’s heading toward the right destination. However, the greatest danger for investors is mistaking market turbulence for a change in destination. It’s crucial to distinguish between a necessary strategy review and destructive, emotion-driven portfolio tinkering.
A strategy review should be a scheduled, low-frequency event triggered by significant changes in your life, not the market. These triggers are personal and fundamental to your financial plan. They include events like getting married, changing careers, having a child, or receiving a large inheritance. These moments may legitimately alter your long-term goals, risk tolerance, or time horizon, thus warranting a reassessment of your overall strategy. An annual check-in is a good default discipline, but major changes should only be made in response to these life events.
Portfolio rebalancing, on the other hand, is a more frequent, mechanical process designed to keep your asset allocation in line with your targets. For example, if your target is a 60/40 split between equities and bonds, a strong stock market run might shift it to 70/30. Rebalancing simply involves selling some equities and buying bonds to return to your 60/40 target. This can be done on a set schedule (e.g., quarterly or annually) or when allocations drift by a predetermined percentage (e.g., 5-10%). This is a rule-based action, not an emotional one. The following table clarifies the distinction.
| Aspect | Strategy Review | Portfolio Rebalancing |
|---|---|---|
| Frequency | Annual (life-based) | Quarterly or trigger-based |
| Focus | Life circumstances & goals | Asset allocation targets |
| Triggers | Major life events only | 5-10% deviation from target |
| Emotion level | Low – planned review | Potentially high – market driven |
| Action required | Usually none | Buy/sell to realign |
As this comparative analysis from Vanguard shows, the triggers and focus are fundamentally different. Resisting the urge to meddle during market volatility is the defining characteristic of a successful automated investor. Schedule your reviews and stick to them, letting the system handle the rest.
The Discretionary Trading Illusion That Derails Carefully Planned Portfolios
Even with a robust automated plan in place, many investors fall victim to the « discretionary trading illusion. » This is the persistent belief that, while the automated strategy is good for the « main pot, » they can generate superior returns through a small, separate account for « smart » trades based on news, tips, or gut feelings. This discretionary pot often becomes a behavioural sandbox where all the cognitive biases the automated system was designed to prevent run rampant. It’s a gateway to self-sabotage.
The illusion is fuelled by biases like overconfidence and the powerful influence of herd mentality. We overestimate our ability to predict outcomes and are heavily swayed by the actions of others, even when those actions are irrational. Studies on human behaviour in financial contexts reveal a startling pattern: research highlighted by the William & Mary Mason School of Business shows that just 5% of informed investors can influence the decisions of the remaining 95%. This highlights how easily the crowd can pull us away from a sound, long-term plan, especially in a discretionary environment where no hard rules exist.
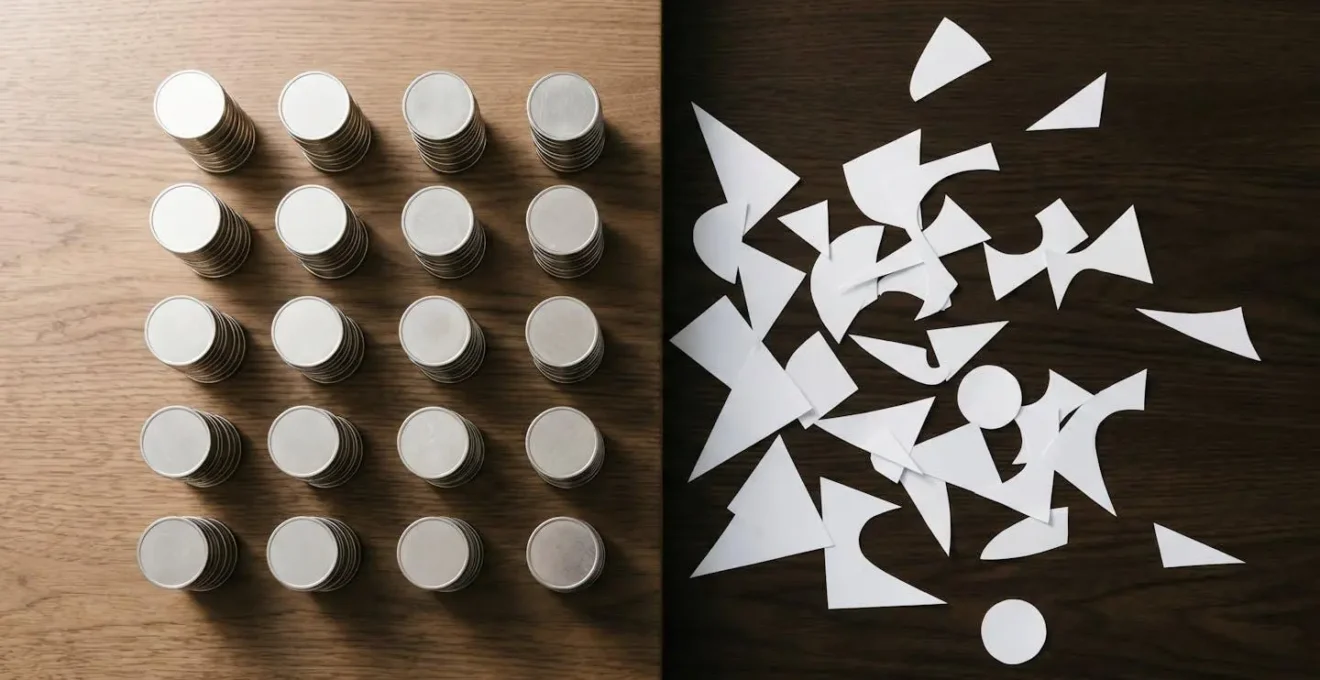
This split approach, as visualized above, creates a conflict. The organised, systematic side of your portfolio is constantly undermined by the chaotic, emotional decisions made on the discretionary side. A winning trade in the « fun » account reinforces the illusion of skill, while losses are often downplayed or forgotten (confirmation bias). Over time, this behaviour almost inevitably leads to underperformance, as the meticulously planned long-term strategy is derailed by a series of impulsive, short-term gambles. The most effective way to combat this is to eliminate the discretionary pot entirely and commit 100% of your investment capital to your automated, rules-based system.
Lump-Sum Investing vs Monthly Drip-Feeding: Which Reduces Your Psychological Stress?
A common dilemma for investors, especially after receiving a bonus, inheritance, or other windfall, is whether to invest it all at once (lump-sum) or drip-feed it into the market over time (pound-cost averaging). From a purely historical and statistical standpoint, the answer is clear. Because markets tend to rise over the long term, getting your money into the market sooner is generally better. In fact, comprehensive research confirms lump-sum investing wins about 66% of the time compared to a 12-month drip-feed strategy.
However, successful investing is not just about statistics; it is about behaviour. The psychologically optimal choice can be different from the mathematically optimal one. The primary psychological risk of lump-sum investing is regret aversion. If you invest a large sum and the market immediately drops 10%, the feeling of regret can be intense, potentially leading you to panic-sell at the worst possible time. This single emotional decision can wipe out the entire statistical advantage of the lump-sum approach.
Pound-cost averaging (drip-feeding) is the superior strategy for managing psychological stress. By spreading the investment over several months, you mitigate the risk of investing everything at a market peak. If the market falls after your first investment, your next purchase will be at a lower price, which feels like a small win. This approach smooths the emotional journey and makes it easier to stick with the plan, which is the most critical factor for long-term success. For many investors, sacrificing a potential small amount of return for a large reduction in stress and a higher probability of staying invested is a very wise trade-off.
How to Automate Your Salary Sweeps to Fund Your ISA on Payday?
The principle of « paying yourself first » is the engine of consistent wealth accumulation. The most effective way to implement this is through a fully automated salary sweep that moves a predetermined portion of your income into your investment accounts on payday, before you even have a chance to see it as disposable cash. This creates « decision friction » for spending and makes saving and investing the path of least resistance. Specifically for UK investors, this means automating transfers into tax-efficient wrappers like a Stocks and Shares ISA or a SIPP.
The setup is a simple, one-time action that pays dividends for decades. Here is a concrete process:
- Set a Standing Order: The simplest method is to set up a standing order from your primary current account to your investment account (e.g., your ISA provider). Schedule it for the day immediately following your payday.
- Define Your Allocations: Decide on a clear percentage-based allocation. A common model is to allocate 15-20% of your gross salary towards long-term investments, with smaller percentages going to an emergency fund or short-term savings goals.
- Use Fractional Shares: Choose an investment platform that supports fractional share purchases. This allows you to set an exact monetary amount for your automated investment (e.g., £250 per month), and the platform will buy the corresponding fraction of shares in your chosen ETF or fund.
- Leverage Payroll Deductions: If your employer offers a workplace pension (like a SIPP) with salary sacrifice, this is the most powerful form of automation. Contributions are taken pre-tax, providing immediate tax relief and reducing your taxable income.
Different automation methods offer varying levels of complexity and efficiency. Choosing the right one depends on your personal circumstances and the options available to you.
| Method | Setup Complexity | Tax Efficiency | Flexibility |
|---|---|---|---|
| Direct from Payroll | Medium | Highest (pre-tax) | Low |
| Bank Standing Order | Low | Standard | High |
| Broker Auto-invest | Low | Standard | Medium |
| Robo-advisor | Very Low | Good (tax-loss harvesting) | Low |
Why Delaying Your Investment Journey by 5 Years Costs You £200,000?
The single most powerful force in investing is compound interest, and its greatest fuel is time. Delaying the start of your investment journey, even by just a few years, can have a devastating and irreversible impact on your final wealth. The figure of £200,000 is not a precise calculation but an illustration of the *magnitude* of the opportunity cost. Depending on market returns and contribution levels, a 5-year delay can easily result in a final portfolio value that is hundreds of thousands of pounds smaller than it could have been.
Consider a simple hypothetical: Two investors both invest £500 per month, earning an average of 7% per year. Investor A starts at age 25 and invests for 40 years. Investor B starts at age 30 and invests for 35 years. At age 65, Investor A’s portfolio would be worth approximately £1.2 million. Investor B’s portfolio would be worth just over £830,000. That 5-year delay cost Investor B nearly £370,000. While this is a simplified example, it powerfully demonstrates the principle.
This isn’t just theory; it’s borne out by real-world investor behaviour. The annual DALBAR study consistently shows a significant « investor gap » between market returns and what the average investor actually earns. The 2024 report, for example, highlighted an investor gap of 8.48%—one of the largest in the last decade. As noted in analysis by Wells Fargo Advisors, this gap illustrates the immense cost of behaviour-driven decision-making (like delaying investment due to fear) compared to a disciplined, early-start strategy. Every year spent on the sidelines is a year you forfeit the powerful work of compounding—a loss you can never recoup.
Key takeaways
- Your biggest financial enemy is not the market; it’s your own emotionally-driven decision-making. Automation is the primary defence.
- Consistency trumps timing. Regular, automated contributions via pound-cost averaging will outperform sporadic, emotionally-charged trades over the long term.
- Build a « Wealth Flywheel »: Automate your salary sweeps, investments, rebalancing, and annual contribution increases to create a self-reinforcing system of wealth accumulation.
How to Automate Your Finances to Guarantee Consistent Wealth Accumulation?
We have established that emotional decisions are destructive and that systematic investing is the solution. The ultimate goal is to connect these automated components into a single, self-reinforcing system: a « Wealth Flywheel. » This flywheel concept moves beyond individual automated actions and integrates them into a continuous cycle that drives unstoppable momentum toward your financial goals. Once set in motion, each component feeds the next, requiring minimal ongoing effort while delivering maximum results.
The flywheel consists of four critical, automated stages that work in concert:
- Automate Capital Capture: This is the initial salary sweep. On payday, a standing order automatically moves a percentage of your income to your investment and savings accounts. The capital is captured before it can be spent.
- Automate Capital Compounding: Your investment platform automatically invests the captured capital into your pre-selected portfolio of diversified, low-cost funds. Your money is put to work immediately, maximizing its time in the market.
- Automate Capital Protection: Your platform or a calendar reminder prompts you to automatically rebalance your portfolio on a quarterly or annual basis. This disciplined action forces you to sell high and buy low, protecting gains and managing risk without emotion.
- Automate Wealth Acceleration: Set an annual calendar reminder to increase your automated contribution amount by a set percentage (e.g., 5%) or in line with your annual pay rise. This ensures your investment rate grows with your income, accelerating your journey to financial independence.
Your Action Plan: Auditing Your Emotional Triggers
- Identify Points of Contact: List every channel through which you consume financial information that could trigger an emotional response (e.g., news apps, social media feeds, specific TV shows, conversations with certain friends).
- Collect Past Decisions: Inventory the last 3-5 major investment decisions you made. For each, note what prompted the action (e.g., a news headline, a market drop, a friend’s tip). Was it part of your plan?
- Assess for Coherence: Confront each past decision with your stated long-term financial goals (e.g., retirement in 20 years). Did the action serve this goal or was it a reaction to short-term noise?
- Gauge Emotional Impact: For each decision, rate the primary emotion you felt at the time on a scale of 1-5 (1=calm, 5=panic/euphoria). Identify patterns where high emotion led to deviation from your plan.
- Build Your Friction Plan: Based on your trigger list, create a plan to introduce « friction. » This could involve deleting news apps from your phone, setting a rule to wait 48 hours before acting on a tip, or limiting portfolio check-ins to once a month.
This flywheel transforms wealth building from a series of stressful, difficult decisions into a quiet, background process. It is the ultimate expression of a behavioural fortress, a system designed not just for convenience, but as a guarantee of consistent, disciplined action over a lifetime.
The journey to financial security is not won by brilliant moves, but by the steadfast avoidance of foolish mistakes. By implementing this fully automated, rules-based strategy, you are not just investing your money; you are architecting a system that ensures your own behaviour is your greatest asset, not your biggest liability. Start building your behavioural fortress today.