The pursuit of high yield from UK retail bonds is a flawed objective; true security comes from mastering the mechanics of capital protection and liquidity risk first.
- Direct bonds offer capital certainty at maturity that funds cannot, but this is contingent on avoiding issuer default and navigating potential liquidity traps.
- Understanding where an instrument sits in the capital structure hierarchy is more critical for risk management than its advertised yield.
Recommendation: Shift your focus from yield-chasing to building a structured bond ladder with staggered maturities. This methodical approach provides predictable cash flow and mitigates interest rate risk.
For the yield-hungry investor, today’s financial landscape presents a frustrating paradox. Savings accounts offer returns that barely pace inflation, while the volatility of the equity market feels like a constant threat to hard-earned capital. The search for a middle ground—a source of meaningful, predictable income without the gut-wrenching swings of stocks—has led many to reconsider the world of fixed income, specifically UK retail bonds and preference shares.
The common advice is to seek out high credit ratings or simply opt for the perceived safety of government gilts. While not incorrect, this view is dangerously incomplete. It overlooks the nuanced, and often hidden, risks that can turn a promising investment into a capital trap. The real challenge is not merely finding a high coupon rate, but constructing a portfolio that is resilient by design.
But what if the key to unlocking secure, high yields was not in chasing the most attractive percentage point, but in methodically de-risking the entire process? This guide adopts a different perspective. We will move beyond the surface-level allure of yield to explore the sophisticated mechanics of capital protection. It is an approach that prioritises understanding the underlying structure of these instruments, the realities of their market liquidity, and the strategic sequencing of purchases.
This article will deconstruct the process, showing how to analyse individual bonds, understand their true position in a crisis, navigate the critical differences between direct ownership and funds, and ultimately, build a robust income-generating machine. This is not about finding a single ‘best’ bond; it is about adopting the mindset of a fixed-income analyst to build a fortress of predictable returns.
To navigate this complex but rewarding landscape, this guide is structured to build your expertise progressively. The following sections will walk you through the essential concepts and strategies for investing in UK fixed-income instruments with confidence.
Contents: A Sophisticated Guide to UK Retail Bonds
- How to Invest Directly in UK Retail Bonds for Predictable Semi-Annual Yields?
- Why Preference Shares Are Often Safer Than Common Equity During Bankruptcies?
- Retail Bonds vs Corporate Bond Funds: Which Offers Better Capital Protection?
- The Liquidity Squeeze That Traps Investors in Niche Fixed Income Instruments
- In What Sequence Should You Buy Different Maturities to Optimise Cash Flow?
- UK Government Gilts vs Corporate Bonds: Which Offers the Best Risk-Reward?
- How to Build a 3-Year Fixed-Rate Bond Ladder for Predictable Returns?
- How to Use UK Gilts and Corporate Bonds to Stabilise Your Investment Returns?
How to Invest Directly in UK Retail Bonds for Predictable Semi-Annual Yields?
Investing directly in retail bonds grants an investor a level of control and predictability that fund structures cannot replicate. The core proposition is a binding contract with an issuer for a fixed coupon, paid semi-annually, and the return of principal at a specified maturity date. However, this simplicity belies the rigorous due diligence required. The primary risk is not market fluctuation but issuer default. Therefore, the analytical focus must be on the financial robustness of the underlying company.
A thorough analysis moves beyond a simple glance at the credit rating. While a rating from Moody’s or S&P is a necessary starting point (with ‘investment grade’ AAA-BBB being the typical comfort zone), a sophisticated investor must perform their own assessment. This involves scrutinising the issuer’s balance sheet, cash flow statements, and key debt service metrics like the EBITDA to net debt ratio. Furthermore, understanding the bond’s specific terms, or covenants, is critical. These clauses can include limitations on future debt issuance and define the bond’s seniority, which dictates its priority in a potential liquidation scenario.
Acquiring these bonds is typically done through platforms like the London Stock Exchange’s Order Book for Retail Bonds (ORB) via a standard brokerage account. It is crucial to recognise that the market is not as homogenous as it once was. An FCA analysis from 2025 shows that while trading is increasingly electronic, a significant portion now occurs on non-UK venues, especially for Euro-denominated bonds. For a retail investor, this underscores the importance of assessing the liquidity and finding a reliable broker before committing capital.
Before investing, a foundational checklist should include:
- Analysing the company’s cash flow and balance sheet strength to assess repayment capability.
- Reviewing key metrics such as the EBITDA to net debt ratio for debt service capacity.
- Checking the bond’s credit rating from agencies (aiming for investment grade).
- Examining bond covenants, including subordination clauses.
- Evaluating exit liquidity by considering the typical trading volume for that specific bond.
Why Preference Shares Are Often Safer Than Common Equity During Bankruptcies?
The concept of « safety » in investing is relative, and its meaning becomes starkly clear during times of corporate distress, such as bankruptcy or liquidation. The primary reason preference shares are considered safer than common equity lies in the legally mandated capital structure hierarchy. This is not a matter of opinion but a fundamental rule of corporate finance that dictates the order of repayment when a company’s assets are distributed.
In a liquidation scenario, creditors are paid first. This group includes senior secured debt holders, followed by unsecured bondholders. Only after all debt obligations have been fully satisfied do shareholders get a claim on the remaining assets. Within the shareholder category, there is a further hierarchy: preference shareholders have priority over common equity shareholders. This means they must be paid their due (typically the par value of their shares plus any accrued, unpaid dividends) in full before common shareholders receive a single penny. In many distressed situations, the assets are exhausted before reaching the common equity level, rendering those shares worthless.
This image illustrates the concept of capital structure through a physical metaphor, showing progressively more fragile layers representing the hierarchy during a liquidation.
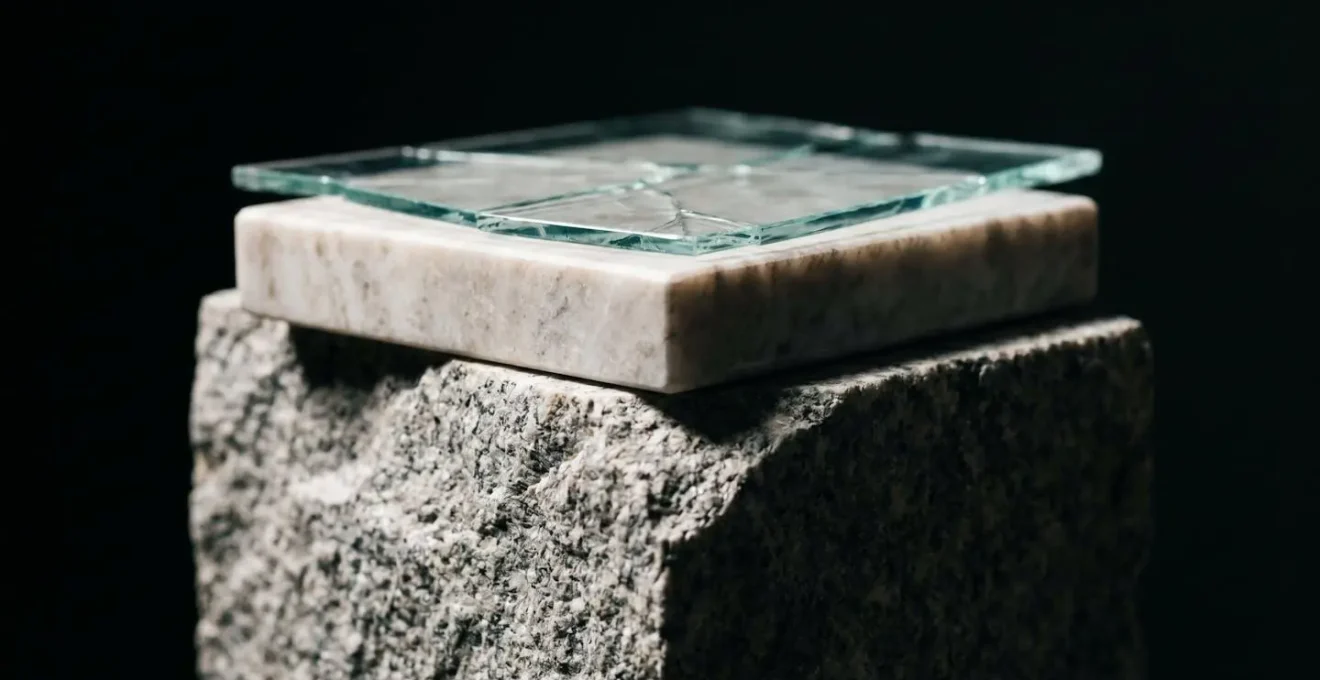
As you can see, the solid base represents the most secure debt, while the delicate top layer signifies common equity. Preference shares occupy the crucial middle ground—more risk than senior bonds, but with a significant protective buffer compared to common stock. This structural advantage is the core of their appeal for cautious, income-oriented investors. While they typically do not offer the unlimited upside potential of common shares, they provide a more defensible claim on the company’s assets, making them a cornerstone of capital protection strategies.
Retail Bonds vs Corporate Bond Funds: Which Offers Better Capital Protection?
The choice between investing in individual retail bonds and a corporate bond fund is a critical decision that hinges on an investor’s priorities, particularly regarding capital protection. While both provide exposure to the fixed-income market, their structures create fundamentally different risk and return profiles. A bond fund offers immediate diversification, spreading risk across hundreds of issues. However, it sacrifices the single most important feature of a direct bond: certainty of principal return at maturity.
When you purchase an individual bond, assuming the issuer does not default, you are guaranteed to receive the bond’s face value back on a specific date. The journey there may involve price fluctuations, but the destination is fixed. In contrast, a bond fund has no maturity date. Its Net Asset Value (NAV) fluctuates daily with changes in interest rates and credit sentiment across all its holdings. There is no guarantee you will get your initial investment back when you choose to sell your fund units. You are entirely subject to the market conditions of that day.
This table summarises the key differences that a sophisticated investor must consider:
| Feature | Direct Retail Bonds | Corporate Bond Funds |
|---|---|---|
| Capital at Maturity | Fixed return of principal (if no default) | NAV fluctuates daily, no guaranteed return |
| Income Stream | Fixed semi-annual coupons | Variable distributions |
| Management Fees | One-off trading commission (£5.95-£20) | Ongoing annual TER (0.5%-1.5%) |
| Liquidity | Can be challenging for niche issuers | Generally easier to sell fund shares |
| Minimum Investment | Often £1,000-£2,000 per bond | Can start from £100 |
This structural distinction is why many discerning investors prefer direct ownership for the core of their fixed-income portfolio. It allows for a more deliberate management of risk, especially interest rate risk. As Luke Hickmore, Investment Director at Aberdeen Investments, points out in an interview with IFA Magazine:
In our view, retail investors may like to consider the short duration market, with bonds that mature in a period between one to five years. This offers a good yield and lowers exit liquidity risk.
– Luke Hickmore, Investment Director – Fixed Income, Aberdeen Investments
This level of precise duration management is only possible with direct bond ownership, making it the superior choice for those prioritising a predictable return of capital over the convenience of a fund.
The Liquidity Squeeze That Traps Investors in Niche Fixed Income Instruments
For all their benefits in providing predictable income, the Achilles’ heel of niche fixed-income instruments is liquidity. Unlike shares in a FTSE 100 company, which can be bought or sold in seconds, many retail bonds trade in a much thinner market. This means that in times of market stress, the ability to sell a holding at a fair price—or at any price—can evaporate. This phenomenon, the liquidity squeeze, is perhaps the most underestimated risk for individual bond investors.
Yield and liquidity often have an inverse relationship. The highest-yielding bonds are frequently issued by smaller, less-known companies, and these are precisely the instruments that suffer the most when market sentiment sours. When investors rush for the exit, the number of buyers willing to take on the risk dwindles. The gap between the buying price (bid) and the selling price (ask) widens dramatically, and sellers may be forced to accept a significant discount to their bond’s theoretical value just to offload it.
This is not a theoretical problem. The Financial Conduct Authority’s analysis of the UK corporate bond market has identified this risk in practice. Their research highlighted two distinct periods of severe illiquidity in recent memory. The first occurred during the spring 2020 coronavirus lockdowns, where, despite high overall market activity, the ability to trade specific bonds deteriorated sharply. A second, more prolonged period of reduced liquidity was observed between mid-2021 and mid-2023. During this time of rising inflation and interest rates, the bid-ask spreads for smaller bond issues widened significantly, effectively trapping investors who needed to sell before maturity.
This risk is why a strategy built solely on chasing the highest available yield is so dangerous. It inherently pushes investors towards the least liquid corners of the market. A prudent approach, therefore, involves balancing the desire for yield with a realistic assessment of a bond’s likely trading volume and the investor’s own time horizon. If there is any chance you will need the capital before the bond matures, prioritising issuers with a larger, more active secondary market presence (such as major banks or utilities) is a non-negotiable part of risk management.
In What Sequence Should You Buy Different Maturities to Optimise Cash Flow?
Optimising cash flow and managing risk in a direct bond portfolio is not about picking individual « winners » but about constructing a deliberate and resilient structure. The most effective and time-tested strategy for this is known as bond laddering. This technique involves dividing your total investment capital into several equal portions and investing each portion in bonds with staggered maturity dates. For example, with £50,000 to invest, you might buy £10,000 worth of bonds maturing in one year, £10,000 in two years, and so on, up to five years.
The primary benefit of this approach is the creation of a predictable and recurring stream of liquidity. Each year, as one « rung » of the ladder matures, you receive your principal back. This provides a regular opportunity to reassess the interest rate environment. If rates have risen, you can reinvest the proceeds into a new bond at the longest end of your ladder (e.g., a new 5-year bond) at the new, higher yields. If rates have fallen, you still have the rest of your ladder locked in at the old, higher rates. This systematic approach smooths out the impact of interest rate fluctuations, a risk that is particularly acute when investing a lump sum into a single long-dated bond.
This visual representation captures the essence of a bond ladder, with staggered maturities creating a steady, ascending flow of returns over time.
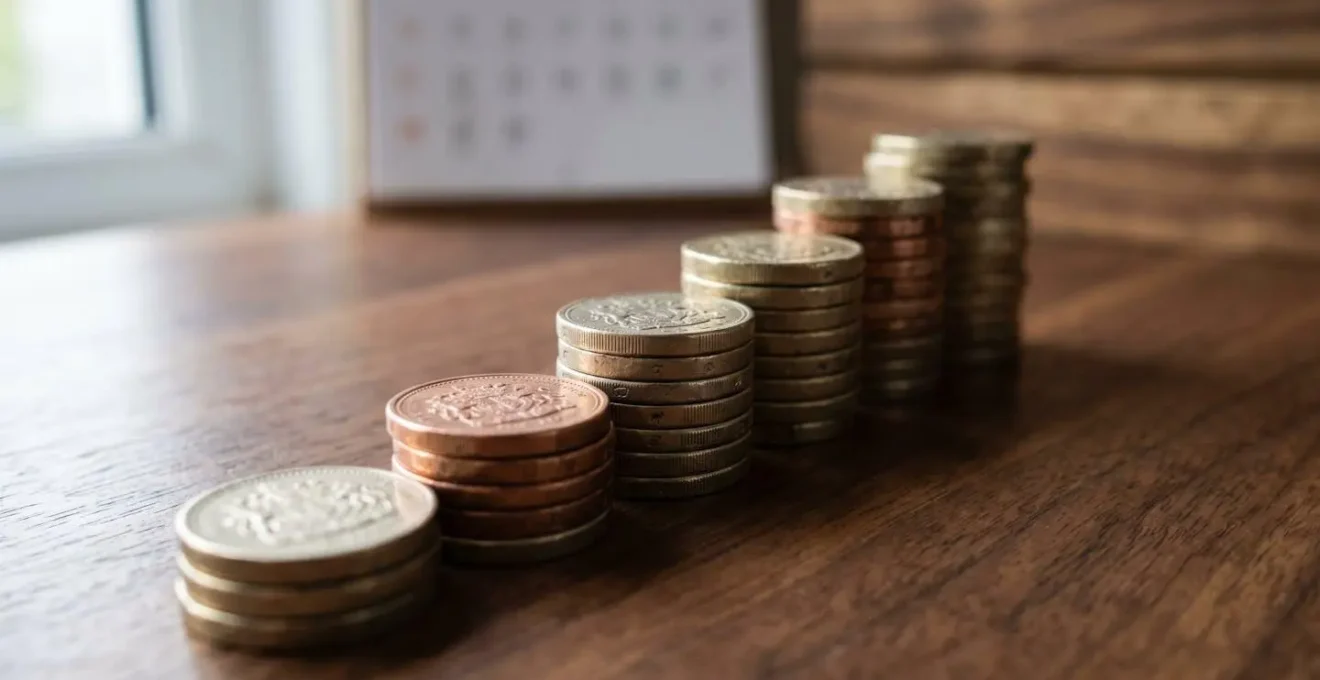
The sequence is therefore one of simultaneous purchase and staggered maturity. You construct the entire ladder at the outset. This creates a powerful engine for generating consistent cash flow and mitigating reinvestment risk. It transforms bond investing from a series of discrete, speculative bets into a systematic, long-term income strategy. The discipline of the ladder removes the temptation to try and « time the market, » which is a fool’s errand, and replaces it with a robust process.
Your Action Plan: Building a UK Retail Bond Ladder
- Determine your investment timeframe and divide capital into equal portions for each maturity year.
- Select bonds from established UK issuers like major banks or National Grid for better liquidity.
- Purchase bonds with staggered maturities (e.g., 1-year, 2-year, 3-year) through platforms like AJ Bell or Hargreaves Lansdown.
- Hold bonds within a Stocks & Shares ISA to shield coupon income from tax where possible.
- When the first bond matures, reinvest the proceeds into a new bond at the ladder’s longest maturity to maintain the structure.
UK Government Gilts vs Corporate Bonds: Which Offers the Best Risk-Reward?
At the heart of any UK fixed-income strategy lies a fundamental choice: UK Government Gilts or Corporate Bonds. These two asset classes form the bedrock of the market, but they offer distinctly different risk-reward profiles tailored to different investor objectives. The decision is not about which is « better » in an absolute sense, but which is more appropriate for a specific role within a portfolio.
UK Government Gilts are, for all practical purposes, considered free of default risk. The UK government has never failed to make a payment on its debt, and its ability to tax and print currency makes a default virtually unthinkable. This unparalleled safety makes gilts the ultimate « safe haven » asset. When markets panic, investors flock to gilts, often bidding up their prices. The trade-off for this security is a lower yield compared to corporate bonds. Investors are paid less because they are taking on less risk. The sheer scale and demand for this safety were demonstrated when the UK Debt Management Office achieved a record £14 billion gilt sale that attracted an astonishing £141 billion in orders.
Corporate bonds, on the other hand, always carry a degree of default risk. To compensate investors for this additional risk, they offer a higher yield, known as the « credit spread. » The level of this spread varies enormously depending on the perceived financial strength of the issuing company. A bond from a blue-chip utility company will offer a much lower yield than one from a more speculative, highly leveraged firm. For investors willing to perform their due diligence and manage this credit risk, corporate bonds are the primary engine for generating a higher level of income.
The following table provides a clear comparison of their defining characteristics:
| Characteristic | UK Government Gilts | UK Corporate Bonds |
|---|---|---|
| Default Risk | Virtually zero – UK government never defaulted | Varies by issuer credit rating |
| Typical Yield | Lower (government backing) | Higher (risk premium) |
| Capital Gains Tax | Exempt | Exempt if qualifying |
| Inflation Protection | Index-linked gilts available (RPI-linked) | Generally fixed nominal returns |
| Market Role | Safe haven asset, portfolio ballast | Income enhancement with managed risk |
Ultimately, a sophisticated portfolio often uses both. Gilts provide the unshakeable foundation and portfolio ballast, while a carefully selected basket of corporate bonds provides the enhanced income stream.
How to Build a 3-Year Fixed-Rate Bond Ladder for Predictable Returns?
Moving from the theory of bond laddering to its practical application requires a concrete plan. Building a short-duration ladder, such as a 3-year fixed-rate structure, is an excellent strategy for investors seeking predictable returns while minimising exposure to long-term interest rate risk. This approach provides a steady stream of maturing capital and a clear, defined income path.
The construction is straightforward. An investor first decides on the total capital to allocate, then divides it into three equal tranches. Each tranche is used to purchase a high-quality bond maturing in one, two, and three years, respectively. The focus should be on established, investment-grade issuers to ensure a high probability of principal return. As the 1-year bond matures, the proceeds are then reinvested into a new 3-year bond, maintaining the ladder’s structure and allowing the investor to capture prevailing interest rates.
A crucial element of this strategy for UK investors is the use of tax-efficient wrappers. Holding these bonds within a Stocks & Shares ISA can shield all the coupon income from income tax. This can dramatically improve the net return, especially for higher-rate taxpayers, and is a simple but powerful optimisation that should not be overlooked.
Case Study: Constructing a £30,000 3-Year Ladder
An investor looking to build a £30,000 ladder could take the following steps using bonds available on the London Stock Exchange’s ORB platform. They would allocate £10,000 to a bond maturing in 2025, £10,000 to one maturing in 2026, and £10,000 to one maturing in 2027. Practical examples could include selecting a Rolls-Royce 3.375% 2026 bond, a Retail Charity Bonds 3.9% 2027 issue, and another suitable bond for the 2025 maturity. These can be purchased through platforms like Hargreaves Lansdown or AJ Bell, with dealing costs typically ranging from £5.95 to £11.95 per trade. In 2025, when the first bond matures, the £10,000 principal would be reinvested into a new bond maturing in 2028, thus perpetuating the 3-year structure.
This practical, step-by-step approach demystifies the process. It transforms a portfolio from a random collection of assets into a disciplined, income-generating machine designed for resilience and predictability.
Key Takeaways
- True capital protection in bonds comes from understanding the capital structure, not just the credit rating.
- Direct bond ownership offers a certainty of principal return at maturity that bond funds cannot structurally provide.
- A bond ladder is the most effective strategy to mitigate interest rate risk and create a predictable income stream.
How to Use UK Gilts and Corporate Bonds to Stabilise Your Investment Returns?
In a world of volatile markets and complex financial products, the primary role of bonds in a diversified portfolio is often misunderstood. It is not simply to generate yield, but to act as a powerful stabilising force. The allure of high returns can lead investors down risky paths; for instance, IG data shows that 68% of retail CFD accounts lose money, a stark reminder of the dangers of leveraged speculation. High-quality bonds, particularly gilts and investment-grade corporates, offer the antidote: a source of stability and negative correlation to equities.
The stabilising effect works in two ways. Firstly, the fixed coupon payments provide a consistent and predictable cash flow, regardless of the daily noise in the stock market. This income acts as a ballast, providing a positive return component even when equity values are falling. Secondly, high-quality government bonds often exhibit a « flight to safety » characteristic. During a stock market crash or a period of economic panic, investors sell risky assets (equities) and buy safe assets (gilts). This surge in demand can cause gilt prices to rise, providing a capital gain that directly offsets some of the losses in the equity portion of the portfolio.
Therefore, using bonds to stabilise returns is not a passive act of simply holding them. It is an active portfolio construction decision. The allocation between gilts and corporate bonds, and between bonds and equities, should be a deliberate choice based on an investor’s risk tolerance and time horizon. A more conservative investor might hold a higher allocation to gilts, prioritising maximum downside protection. An investor comfortable with more credit risk in exchange for higher income might lean more towards a diversified portfolio of corporate bonds. In either case, the bonds are not there to shoot the lights out; they are there to ensure the lights stay on when everything else goes dark.
By combining the near-zero default risk of gilts with the enhanced, yet managed, income from a laddered portfolio of corporate bonds, an investor can construct a fixed-income allocation that is robust, resilient, and acts as a powerful stabiliser for their entire investment strategy.
The logical next step is to move from theory to action by beginning the due diligence process on specific, high-quality bond issuers that fit your newly defined laddering strategy.
Frequently Asked Questions on How to Use UK Gilts and Corporate Bonds to Stabilise Your Investment Returns?
How do bonds stabilize returns during market crashes?
High-quality government bonds often rise when stock prices fall due to the ‘flight to safety’ phenomenon, where investors move to safer assets, automatically cushioning portfolio value.
What’s the ‘110 minus your age’ bond allocation rule?
This traditional rule suggests your bond allocation percentage should equal 110 minus your age, though it requires adjustment in today’s low-rate environment based on personal risk tolerance.
Why are bonds considered negative correlation assets?
When interest rates rise, bond prices typically fall, but during equity market stress, quality bonds often appreciate as investors seek safety, providing portfolio balance.