Securing a guaranteed retirement income is not about chasing the highest rate, but about methodically eliminating financial risk to achieve true peace of mind.
- Accepting your provider’s first offer (the « loyalty penalty ») can cost you tens of thousands in lifetime income.
- Your health and lifestyle are valuable assets that can significantly boost your guaranteed income through an enhanced annuity.
Recommendation: Use the Open Market Obligation to compare quotes from multiple providers and build an « income fortress » tailored to your life, not your old pension scheme’s convenience.
The transition from accumulating a pension pot to turning it into a reliable income is one of the most significant financial moments of your life. For decades, you’ve navigated the uncertainties of the stock market, focusing on growth. Now, the goal shifts entirely. The priority is no longer about potential gains; it’s about absolute certainty. Many retirees are told to simply « buy an annuity, » but this advice often overlooks the profound emotional need for unwavering financial security.
The real challenge isn’t just generating an income; it’s engineering an income that you cannot outlive, that protects your loved ones, and that shields your lifestyle from future economic shocks. This process goes beyond a simple transaction. It is an act of « certainty engineering, » where every choice is a deliberate step toward building an impenetrable income fortress. While some focus on the flexibility of drawdown, this path comes with the persistent stress of market volatility, a worry many retirees are eager to leave behind.
This guide abandons the complex jargon and focuses on what truly matters: achieving complete financial peace of mind. We will explore how to strategically convert your SIPP into a guaranteed lifetime income, not by gambling on market performance, but by making informed decisions that lock in security. We’ll demystify the process, revealing how to avoid costly penalties, leverage your personal circumstances for a better outcome, and build a retirement income plan that delivers on its one true promise: a worry-free future.
To help you navigate these critical decisions, this article is structured to walk you through each step of the process, from securing the best rate to protecting your legacy. Below is a summary of the key areas we will cover.
Summary: Your Guide to a Guaranteed Retirement Income
- How to Shop the Open Market to Secure the Highest UK Annuity Rate?
- Why Taking the First Annuity Offer From Your Pension Provider Costs You £10,000?
- Single vs Joint Life Annuities: Which Protects Your Spouse Better After You Pass?
- The Inflation-Linked Omission That Halves Your Purchasing Power Over 20 Years
- How to Combine Drawdown and Annuities for the Perfect Retirement Balance?
- Fixed Drawdown vs Flexible Income: Which Sustains Your Wealth Longer?
- When is the Exact Right Age to Lock in a Guaranteed Income for Life?
- How to Use Your Medical History to Boost Your Guaranteed Retirement Income?
How to Shop the Open Market to Secure the Highest UK Annuity Rate?
The single most important rule when securing a lifetime income is to exercise your ‘Open Market Option’. This legal right allows you to take your pension pot to any provider, not just the one you’ve saved with. Failing to do so is like accepting the first offer on your house without seeing what other buyers are willing to pay. The difference in income can be staggering. Shopping the market effectively means you are putting providers in competition with each other for your business, ensuring you receive the best possible rate based on current market conditions.
For example, the current UK annuity rates for 65-year-olds show a £100,000 pension pot can generate an annual income of £7,703. However, this figure is a benchmark; the actual offer you receive can vary significantly between providers. This variance isn’t arbitrary; it reflects each company’s appetite for risk, their investment performance, and their current business strategy. By comparing quotes from a wide range of providers, you tap into this competitive landscape to your advantage.
The process of shopping around is not as daunting as it may seem. It is a structured exercise in diligence that pays dividends for the rest of your life. To ensure you navigate this process methodically, follow a clear plan of action.
Your Action Plan: Securing the Best Annuity Rate
- Request your ‘wake-up pack’ from your pension provider 4-6 months before your planned retirement date to get the process started.
- Use whole-of-market brokers and online comparison tools to gather quotes from a wide range of annuity providers.
- Fully disclose all health and lifestyle information, no matter how minor it seems, to see if you qualify for a significantly higher enhanced rate.
- Request quotes with identical features (e.g., joint life, inflation protection) from 3-4 of the top providers simultaneously to create a clear comparison.
- Pay close attention to quote expiry dates, which are typically 14-30 days, and use this timeframe to finalize your decision.
- Once you have chosen the best offer, complete the application with your new provider before the competitive quote expires.
Why Taking the First Annuity Offer From Your Pension Provider Costs You £10,000?
For years, you’ve diligently saved with a single pension provider, building a relationship based on trust. It’s natural to assume they will reward your loyalty with the best possible retirement income deal. Unfortunately, the opposite is often true. Accepting the default annuity offer from your existing provider without shopping around is one of the most expensive mistakes a retiree can make. This « loyalty penalty » can cost you tens of thousands of pounds over the course of your retirement.
Pension companies are not legally obligated to tell you that you could get a better rate elsewhere. Their initial offer is often based on standard, non-competitive rates, and they may not have automatically assessed you for an enhanced annuity, even if you qualify. The difference this makes is enormous. An analysis by Which? Money found that by shopping around, retirees could secure a significantly better deal. For instance, when they ran quotes for a 65-year-old, some providers offered up to 15% more for an enhanced annuity compared to a standard one from another. This isn’t a small change; it’s a fundamental difference in your annual lifestyle.
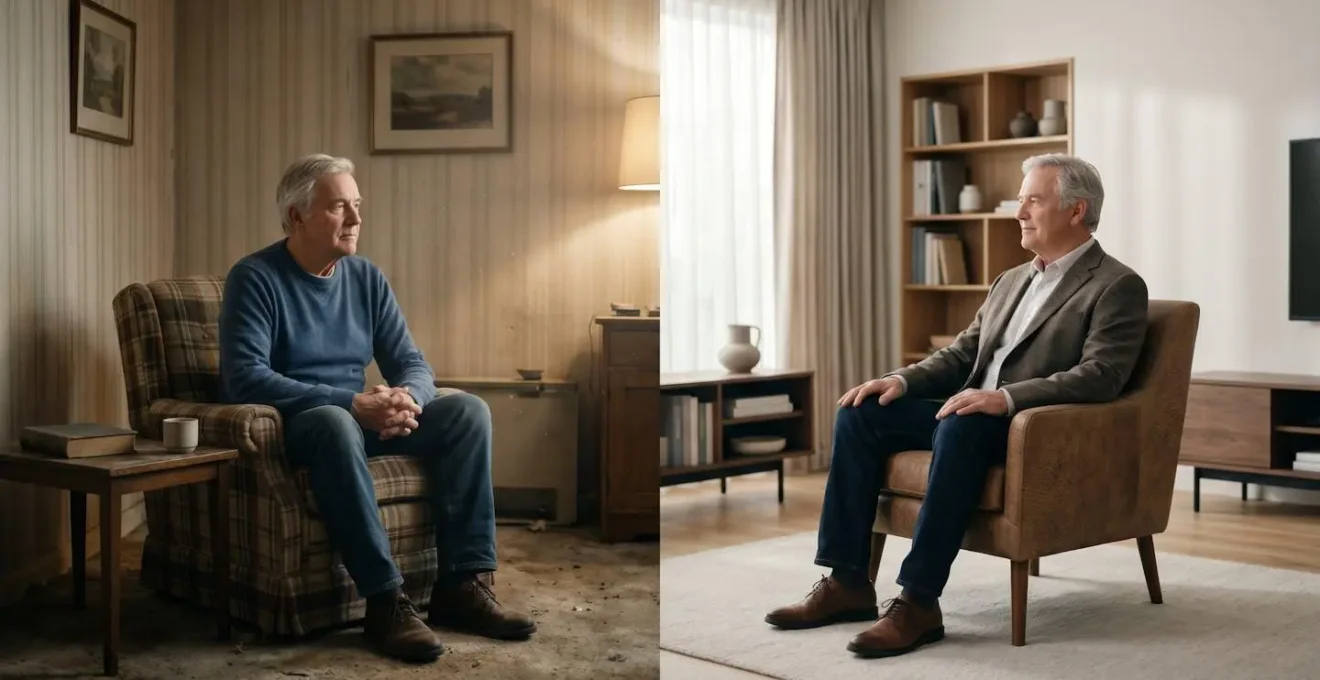
The visual contrast between a modest retirement and a comfortable one is a direct result of these decisions. The extra income secured through the open market can mean the difference between worrying about bills and enjoying your hobbies, travel, and time with family. It is the tangible reward for not settling for the first offer you receive.
The following table illustrates the stark financial reality of the loyalty penalty, based on a £100,000 pension pot. This comparison of potential annuity rates highlights the vast difference between a default offer and what can be achieved on the open market.
| Provider Type | Annual Income (£100k pot) | 25-Year Total |
|---|---|---|
| Default Provider Rate | £6,500 | £162,500 |
| Best Open Market Rate | £7,703 | £192,575 |
| Enhanced Rate (health) | £8,250 | £206,250 |
Single vs Joint Life Annuities: Which Protects Your Spouse Better After You Pass?
One of the most profound decisions in « certainty engineering » is how your income will provide for your loved ones after you’re gone. This choice centres on single versus joint life annuities. A single life annuity provides the highest possible income, but it is based solely on your life. When you pass away, the payments stop completely, potentially leaving your surviving spouse or partner in a difficult financial situation.
In contrast, a joint life annuity is designed to build a financial bridge for your partner. It provides a lower starting income than a single life annuity, but in return, it guarantees that a portion of the income will continue to be paid to your named dependant for the rest of their life after you die. This is the ultimate act of financial protection for the person you care about most. You are consciously accepting a slightly smaller income today to ensure their security tomorrow.
The trade-off is clear and must be weighed carefully. Typically, joint life annuities provide a 50% reduction in income for the surviving spouse, though you can often choose other percentages, such as 66% or 100%, which would further reduce your initial income. The decision depends entirely on your partner’s own financial resources. If they have a substantial pension of their own, a single life annuity might be appropriate. If they are financially dependent on you, a joint life annuity is an essential safety net. This isn’t just a financial calculation; it’s a conversation about shared futures and mutual peace of mind.
The Inflation-Linked Omission That Halves Your Purchasing Power Over 20 Years
Securing a guaranteed income is a fantastic first step, but what happens when the cost of living rises year after year? An income that seems comfortable today could feel restrictive in a decade. This is the silent threat of purchasing power erosion. A ‘level’ annuity pays the same fixed amount for life. While it offers the highest starting income, its real-world value will steadily decline due to inflation. Over a 20-year retirement, even modest inflation can effectively halve what your money can buy.
As the experts at Which? Money point out, the choice involves a significant trade-off.
Opting for an annuity that pays a fixed amount every year means that over time you’ll find your income doesn’t stretch as far because it isn’t rising in line with inflation. Inflation-linked annuities ensure that your payments increase each year, but you’ll need to weigh up whether you’re willing to accept the lower starting income they offer. It could take you a decade before this income matches what you would have received at the beginning from a level annuity.
– Which? Money, Which? Annuity Rates Guide
The alternative is an ‘escalating’ or ‘inflation-linked’ annuity. This type of annuity starts with a lower income, but the payments increase each year, typically by a fixed percentage (e.g., 3%) or in line with an inflation measure like the Retail Prices Index (RPI). You are sacrificing some income in the early years of retirement to protect your lifestyle in the later years. This is a critical piece of certainty engineering: are you planning for your first year of retirement, or for your last?
The following table, based on data illustrating indexation options, shows how different choices impact your income over time, assuming a level starting income of £7,703.
| Indexation Type | Starting Income | Year 10 Income (est.) | Year 20 Income (est.) |
|---|---|---|---|
| Level (no increase) | £7,703 | £7,703 | £7,703 |
| Fixed 3% | £6,200 | £8,332 | £11,194 |
| RPI-linked | £5,800 | Variable | Variable |
How to Combine Drawdown and Annuities for the Perfect Retirement Balance?
For some retirees, the choice between the absolute security of an annuity and the flexibility of drawdown feels like an impossible compromise. But it doesn’t have to be an all-or-nothing decision. A powerful strategy is to combine both, creating a hybrid approach that offers the best of both worlds: a foundation of security with a layer of flexibility on top.
This strategy is often framed by the ‘Needs, Wants, and Wishes’ framework. First, you calculate your essential living costs—your ‘Needs’ like housing, bills, and food. You use a portion of your pension pot to buy an annuity that generates enough guaranteed income to cover these non-negotiable expenses. This builds your income fortress, ensuring your basic lifestyle is secure no matter what happens in the markets. The remaining portion of your pot stays in a flexi-access drawdown plan. This fund can be used to pay for your ‘Wants’—such as holidays, hobbies, or a new car—and your ‘Wishes’, like leaving an inheritance for your family.
Case Study: Phased Annuitisation
A ‘phased annuitisation’ strategy involves buying smaller annuities over time. Research from Standard Life shows this can be highly effective. Their analysis revealed that a combined approach, where someone purchases annuity slices every five years from age 65 to 80 while also using drawdown, provides a higher total income over a 25-year retirement. The study found this phased strategy could result in a total income of £259,115, outperforming a pure drawdown or immediate annuity strategy. This method allows you to benefit from potentially higher annuity rates as you age while maintaining flexibility.
This balanced approach removes the primary source of retirement anxiety by guaranteeing your core expenses are met. It provides the psychological freedom to enjoy the flexible portion of your savings without the fear of running out of money for essentials. It’s a masterful piece of certainty engineering.
Fixed Drawdown vs Flexible Income: Which Sustains Your Wealth Longer?
For those drawn to the flexibility of drawdown, it’s crucial to understand the inherent risks that an annuity is designed to eliminate. With drawdown, your pension pot remains invested, and you draw an income from it. While this offers control, it also exposes you to ‘sequence of returns risk’. This is the danger of a market downturn occurring in the early years of your retirement. When you are drawing an income from a pot that has just lost value, you have to sell more units to get the same amount of cash, permanently depleting your capital and jeopardizing the longevity of your fund.
Stress-testing models reveal the devastating impact this can have. For example, stress-testing reveals that a 30% market drop in year 2 of retirement can cripple a drawdown pot’s ability to provide a sustainable income for life. An annuity, by contrast, is completely insulated from this risk. Your income is guaranteed, regardless of whether the market soars or crashes. This is the core trade-off: the potential for market growth versus the guarantee of market immunity.
The choice between a fixed, guaranteed income and a flexible, variable one comes down to your personal tolerance for risk and your desire for peace of mind. While drawdown may sustain wealth longer in a consistently rising market, it can also lead to rapid wealth depletion in a volatile one.
Case Study: The Impact of Sequence Risk
Consider Simon, 60, who had a SIPP of £230,000 to top up his main pension. His financial plan involved drawing down funds to meet his income needs. However, the plan did not account for poor market performance. Under one scenario where he drew down the required income and investment growth was flat, the simulation showed he would have exhausted his pension pot just before his 75th birthday. An annuity would have continued paying an income for the rest of his life.
An annuity is a contract that exchanges this uncertainty for a predictable, lifelong payment. For retirees whose primary goal is security, this exchange is often the most logical and comforting choice.
When is the Exact Right Age to Lock in a Guaranteed Income for Life?
Timing is a critical factor in maximising your guaranteed income. The simple rule is: the older you are when you buy an annuity, the higher your annual income will be. This is because the provider expects to pay you for a shorter period. The difference between buying at 60 versus 70 can be substantial, adding thousands of pounds to your income each year for the rest of your life.
For example, data shows that a 60-year-old with a £100,000 pot might receive an income of around £6,740 per year. By waiting until age 70, that same pot could generate a much higher income. The annuity rate at age 70 rises to 8.25%, meaning the annual income could be around £8,250. This is a significant uplift gained simply by waiting. This is why phased annuitisation can be so powerful; you can secure progressively better rates on portions of your pension as you age.
However, age is not the only factor. Annuity rates are also closely linked to the wider economy, particularly the yields on long-term government bonds (gilts) and the Bank of England’s base interest rate. As Holly Tomlinson of Quilter Financial Planning explains, this can create windows of opportunity.
Annuity rates are closely tied to government bond yields, which can be influenced by changes in interest rates. A reduction in the base rate may lead to lower bond yields, potentially resulting in less favourable annuity rates for retirees. Indeed, annuity rates drifted downwards in 2024 following two interest rate reductions, but then soared during the gilt turmoil in January 2025.
– Holly Tomlinson, Quilter Financial Planning
There is no single « perfect » age to buy an annuity, as it depends on a combination of your personal health, your need for income, and the prevailing economic conditions. The key is to be aware of how these factors work together and to seek advice when you are ready to turn your pension pot into an income stream.
Key Takeaways
- Never accept your current provider’s first offer. Always use the Open Market Option to compare quotes.
- Your health and lifestyle are assets. Full disclosure can lead to a significantly higher income via an enhanced annuity.
- A guaranteed income is an exchange of market uncertainty for absolute peace of mind; frame your decisions around this goal.
How to Use Your Medical History to Boost Your Guaranteed Retirement Income?
One of the most overlooked yet powerful tools for increasing your guaranteed income is your own medical history. An enhanced annuity (or ‘impaired life’ annuity) pays a higher income to individuals with health conditions or lifestyle factors that could potentially reduce their life expectancy. From the provider’s perspective, they expect to make payments for a shorter duration, so they can offer a better rate. Many people mistakenly believe this only applies to severe illnesses, but a wide range of common conditions can qualify you.
Insurers assess over 1,500 different conditions, and you don’t need to be seriously ill to benefit. Common issues like high blood pressure, high cholesterol, type 2 diabetes, or even a high BMI can lead to a significant uplift in your income. Smokers or those with a history of smoking can also qualify. The increase can be substantial; recent market data shows that those qualifying for enhanced rates might see over 7%, a rate that represents a major boost to lifetime income.
It is therefore absolutely critical to disclose your full medical history and lifestyle details to any broker or provider you approach. This includes any medication you take, past surgeries, and even your postcode, as some providers factor in regional life expectancy data. Being modest or private about your health during this process is, financially speaking, a mistake. Your health history is a financial asset; use it to secure the highest possible guaranteed income.
The following common conditions could qualify you for a higher income:
- High blood pressure, even if it is well-controlled by medication.
- Type 2 diabetes, regardless of how it is managed.
- High cholesterol, including for those taking statins.
- Smoking history, covering both current smokers and those who have quit.
- A BMI over 30 or other significant weight-related issues.
- Regular alcohol consumption (e.g., over 14 units per week).
Your journey to absolute financial peace of mind begins not with a signature, but with a simple comparison. Start the process today by requesting your ‘wake-up pack’ and exploring the open market to build the secure future you’ve earned.
Frequently Asked Questions on SIPP Annuities
What happens to a single life annuity when I die?
With a standard single life annuity, all payments cease upon your death. There is no lump sum or ongoing income paid to your estate or dependants. However, you can add features like a ‘guarantee period’, which ensures payments continue for a set term (e.g., 10 years) to your beneficiaries if you pass away within that period.
How does a joint life annuity protect my partner?
A joint life annuity provides a safety net by continuing to pay an income to your named partner if you die before they do. This income is typically set at a reduced rate, such as 50% of the original payment, and will last for the rest of their life, ensuring they have ongoing financial support.
Can I protect other dependents besides my spouse?
Yes. While a joint life annuity is typically for a spouse or partner, a ‘guaranteed period’ annuity can protect any dependant. If you select a 10-year guarantee period and pass away after 3 years, the income will continue to be paid to your nominated beneficiary for the remaining 7 years.