Your current protection policies likely contain critical, invisible gaps that create an illusion of safety while leaving your family exposed to financial ruin.
- Relying on « death in service » benefits is a dangerous gamble, as coverage evaporates the moment your employment status changes.
- The default state for most families without specific income protection is a catastrophic drop to just £116.75 per week in Statutory Sick Pay.
Recommendation: Stop assuming you are covered. Conduct a forensic audit of your existing policies against your family’s true financial needs immediately.
As the primary breadwinner, you carry the immense responsibility of your family’s financial security. You’ve likely taken steps to mitigate risk, perhaps by securing life insurance or relying on your employer’s « death in service » benefit. The common advice is to « review your policies » after major life events like marriage, a new home, or the birth of a child. This is sensible, but it is dangerously incomplete. It fosters a passive, check-box mentality towards a subject that demands rigorous, proactive scrutiny.
This approach fails to address the brutal reality: most protection portfolios are not merely suboptimal, they are fundamentally flawed. They are riddled with gaps, outdated assumptions, and a misplaced reliance on temporary solutions. These vulnerabilities are often invisible until the moment of crisis, at which point it is too late. The difference between what you *think* you have and what your family would actually *receive* can be the difference between stability and destitution.
But what if we reframe the process entirely? What if, instead of a casual « review, » you were to conduct a forensic audit? This is not a routine financial task; it is a deliberate stress-test designed to unearth the fatal, often hidden, gaps between your perceived security and the harsh reality of a critical illness or loss of income. This guide will not offer you platitudes. It will provide a framework to dissect your existing protection, challenge your assumptions, and build a truly resilient financial shield for those who depend on you.
We will systematically dismantle the common points of failure in personal protection planning. This structured approach will give you the clarity and tools needed to ensure your family’s financial future is not left to chance.
Summary: A Forensic Guide to Your Financial Shield
- How to Calculate the Exact Amount of Life Cover Your Family Truly Needs?
- Why Relying Solely on Your Employer’s Death in Service Benefit is Dangerous?
- Critical Illness Cover vs Income Protection: Which Do You Prioritise on a Budget?
- The Non-Disclosure Error That Voids 20% of UK Life Insurance Claims
- When to Review and Upgrade Your Protection Policies After a Major Life Event?
- The Underfunding Mistake That Forces UK Families Into Expensive Short-Term Debt
- Why High-Net-Worth Individuals Need Umbrella Insurance Beyond Standard Home Policies?
- How to Shield Your Wealth From Ruinous UK Litigation and Compensation Claims?
How to Calculate the Exact Amount of Life Cover Your Family Truly Needs?
Generic rules of thumb, such as « 10 times your annual salary, » are a reckless starting point for calculating life cover. They ignore the unique contours of your family’s financial landscape, particularly your debts, future liabilities, and the true cost of replacing your contribution to the household. A forensic audit demands precision. The goal is not to find a comfortable number, but to calculate the exact figure required to maintain your family’s standard of living and secure their future without compromise.
This calculation must be comprehensive, accounting for immediate and long-term financial obligations. It should clear all outstanding debts, fund educational aspirations, cover ongoing household bills for a defined period, and even account for the services you provide that would need to be replaced, such as childcare or household management. Anything less is a planned shortfall. To achieve this, you need a structured framework that leaves no stone unturned.
Your Action Plan: The D.E.B.T.S. Calculation Framework
- Debts: Calculate the total of all existing debts, including credit cards, car loans, student loans, and any personal loans. The mortgage is often the largest component.
- Education: Estimate all future education costs. This includes any current private school fees plus projected university expenses for each child.
- Bills: Determine your family’s total annual bills. This must cover mortgage or rent payments, utilities, council tax, insurance premiums, and all other recurring household expenses.
- Time: Multiply the annual bills by the number of years until your youngest child is financially independent (e.g., age 21 or 25). This creates the core income replacement fund.
- Successor Costs: Account for the cost of replacing your non-financial contributions. If you are the primary caregiver, what would full-time childcare cost? If you manage the home, what would those services cost to outsource?
By completing this forensic calculation, you replace guesswork with certainty. The final number is not an aspiration; it is the minimum capital sum your family requires to be truly protected. This figure becomes the non-negotiable benchmark against which you must audit your existing policies.
Why Relying Solely on Your Employer’s Death in Service Benefit is Dangerous?
One of the most common and dangerous assumptions in personal finance is that an employer’s « death in service » benefit is a substitute for personal life insurance. It is not. This benefit, typically a multiple of your salary paid out as a lump sum, creates a fragile illusion of safety. It is a ‘golden handcuff’ that ties your family’s security directly to your current employment status, exposing them to a catastrophic vulnerability gap the moment that status changes.
Consider the realities of a modern career path: sabbaticals, redundancies, career breaks to care for family, or transitions to freelance or contract work are all common. In almost every scenario, your death in service benefit ceases immediately. It is not portable, and it is not your property. As the analysis from BaldwinClarke shows, this creates significant coverage gaps. The benefit may also be inadequate; a ‘4x salary’ payout may have been sufficient when you joined the company, but it quickly becomes dwarfed by a growing mortgage and an expanding family. This is a risk you cannot afford to outsource.
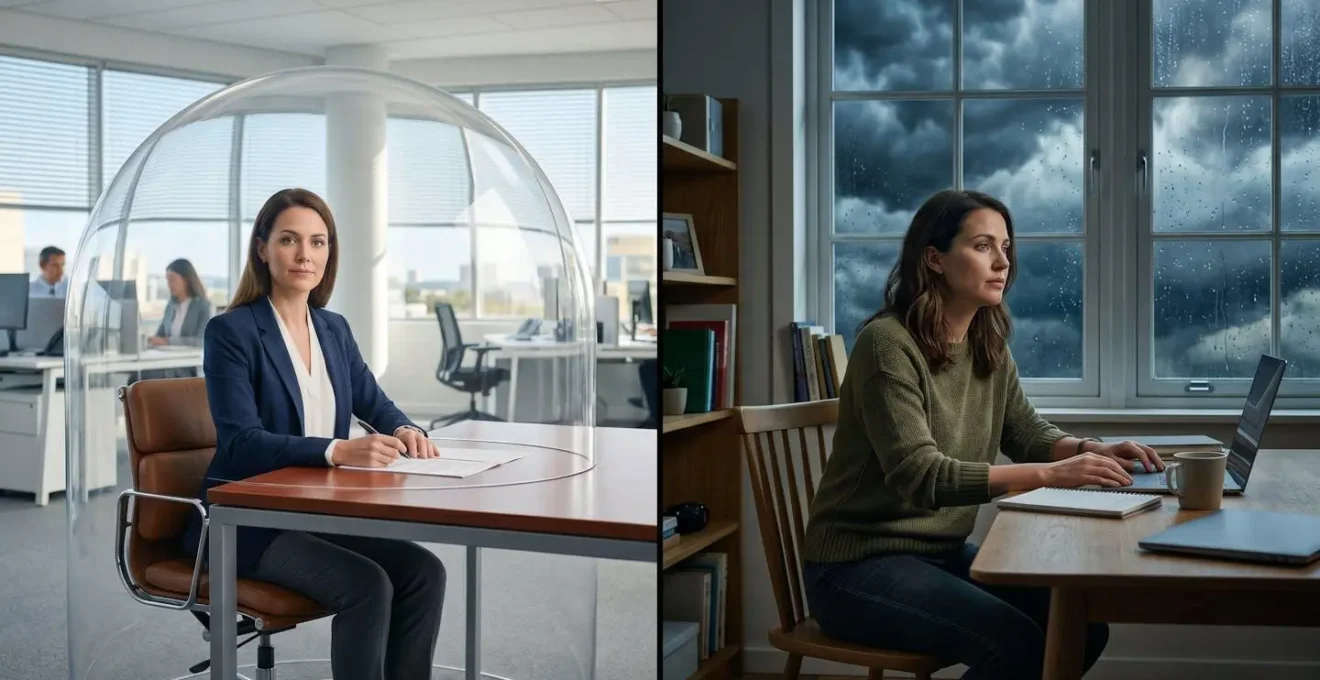
This image starkly illustrates the reality. The protection offered by an employer is conditional and temporary. True financial security for your family must be built on a foundation of personally owned policies that you control. These policies remain in force regardless of your employment, providing a constant, reliable shield against the unthinkable. Your employer’s benefit should be viewed as a welcome bonus, an additional layer of protection, but never as the cornerstone of your family’s financial plan.
Critical Illness Cover vs Income Protection: Which Do You Prioritise on a Budget?
While life insurance addresses the ultimate tragedy, a far more probable event is a serious illness or injury that prevents you from working. This is where the choice between Critical Illness (CI) Cover and Income Protection (IP) becomes paramount. They are not interchangeable. Confusing their roles is a critical error. In a single year, insurers pay out a colossal £8 billion in combined protection claims, demonstrating how vital these policies are for UK families. The key is to understand which type of policy addresses the most likely and most damaging risk to your finances.
CI cover pays a one-off, tax-free lump sum if you are diagnosed with one of a specific list of serious conditions defined in the policy. IP, on the other hand, provides a regular, recurring tax-free income if you are unable to work due to any illness or injury. The choice is not about which is « better, » but which is more appropriate for your immediate priorities on a limited budget. A lump sum from CI can clear a mortgage or pay for medical adaptations, while a monthly income from IP replaces your salary and keeps the household running. The following table breaks down the fundamental differences:
| Factor | Critical Illness Cover | Income Protection |
|---|---|---|
| Payout Type | Lump sum (average £67,600) | Monthly payments (up to 70% salary) |
| Conditions Covered | 52+ specified conditions only | Any illness/injury preventing work |
| Best For | High-impact events (cancer, stroke) | High-likelihood scenarios (back injury) |
| Claims Success Rate | 91.5% (Aviva 2024) | Higher overall acceptance |
| Support Services | Limited | Rehabilitation, mental health support |
On a strict budget, the priority must be Income Protection. While a cancer diagnosis is devastating, a bad back, stress, or a musculoskeletal injury is statistically far more likely to take you out of work for an extended period. IP covers any medical reason for being unable to work, providing a durable financial lifeline. CI is an excellent and important addition, but protecting your monthly income stream is the single most critical action to prevent financial collapse.
The Non-Disclosure Error That Voids 20% of UK Life Insurance Claims
Holding a policy is meaningless if it won’t pay out when your family needs it most. One of the most tragic and entirely avoidable reasons for a claim being declined is non-disclosure. This isn’t necessarily about deliberate fraud; it is often a simple, honest mistake made during the application process. Forgetting to mention a past health issue, understating your alcohol consumption, or failing to disclose a risky hobby can give an insurer legal grounds to void the policy, returning your premiums and leaving your dependents with nothing.
The principle of ‘utmost good faith’ governs insurance contracts. It places the responsibility squarely on you to volunteer all relevant information, whether you are explicitly asked about it or not. Insurers are not just looking for major events. They require a full picture, including mental health consultations, prescriptions (even temporary ones), and social habits like smoking or vaping. Insurers are entitled to decline claims for reasons you might not expect, as illustrated by one major provider.
6.3% of critical illness claims were declined due to the customer’s condition not meeting the definition for the condition we cover.
– Royal London, 2024 Claims Statistics Report
While this quote highlights denials based on policy definitions, an even larger portion of claims across the industry are rejected due to non-disclosure. The only way to bulletproof your application is to be meticulous. Before applying, you should request a summary of your GP medical records. Review it carefully and ensure every consultation, diagnosis, and prescription from at least the last five years is disclosed on your application form. It is a painstaking process, but it is the only way to guarantee the contract you sign is unbreakable.
When to Review and Upgrade Your Protection Policies After a Major Life Event?
Securing your initial policies is only the first step. Protection is not a « set and forget » product. Your life is dynamic, and your coverage must evolve in lockstep. A policy that was perfect five years ago could be dangerously inadequate today. The industry is responding to this need for ongoing security, with a record 247,000 individual income protection policies sold in 2023, the highest number since the year 2000. This indicates a growing awareness that personal protection needs active management.
Major life events are the most obvious triggers for a review. These moments fundamentally alter your financial responsibilities and, therefore, your protection needs. A new mortgage increases your debt, the birth of a child adds a new dependent, a significant salary increase raises the level of income that needs replacing, and a divorce can completely change beneficiary designations and financial obligations. Waiting for a formal « annual review » is not enough; you must conduct an immediate audit whenever your circumstances change significantly.
A proactive review should be a structured process. It’s an opportunity to ensure your cover remains fit for purpose and that you are benefiting from any new market developments or contractual rights. Your audit should cover several key areas:
- Coverage Adequacy: Does your current level of cover still align with your D.E.B.T.S. calculation? Have your debts or family size increased?
- Beneficiaries: Are the beneficiaries on your policy still correct? This is crucial after a marriage, divorce, or birth.
- Policy Terms: Have any of your policies lapsed? Are the premiums still sustainable?
- Guaranteed Insurability Options (GIOs): Many policies allow you to increase your cover after specific life events without further medical underwriting. Have you missed an opportunity to use a GIO?
- Estate Planning: Have changes in inheritance tax law affected how your policies should be structured, for example, by being written in trust?
This active management transforms your policies from static documents into a living, responsive financial shield.
The Underfunding Mistake That Forces UK Families Into Expensive Short-Term Debt
The single greatest shock to a family’s finances is not death, but a sudden and prolonged loss of income. Many people assume some form of safety net exists, but the reality is brutal. The state provides a minimal buffer, and without personal income protection, the financial cliff-edge is terrifyingly close. The UK’s Statutory Sick Pay (SSP) provides just £116.75 per week as of 2024. This is a non-negotiable fact. Compare that figure to your family’s weekly outgoings—mortgage, food, utilities, transport. The gap is not a gap; it is a chasm.
This is the underfunding mistake. It is the failure to insure your most valuable asset: your ability to earn an income. Relying on SSP and savings is a strategy that can be measured in weeks, not months or years. Once savings are depleted, families are forced to turn to high-interest credit cards and expensive short-term loans just to cover basic living costs. This creates a spiral of debt that can be impossible to escape from, even if you eventually return to work. The financial and emotional stress is immense and entirely preventable.
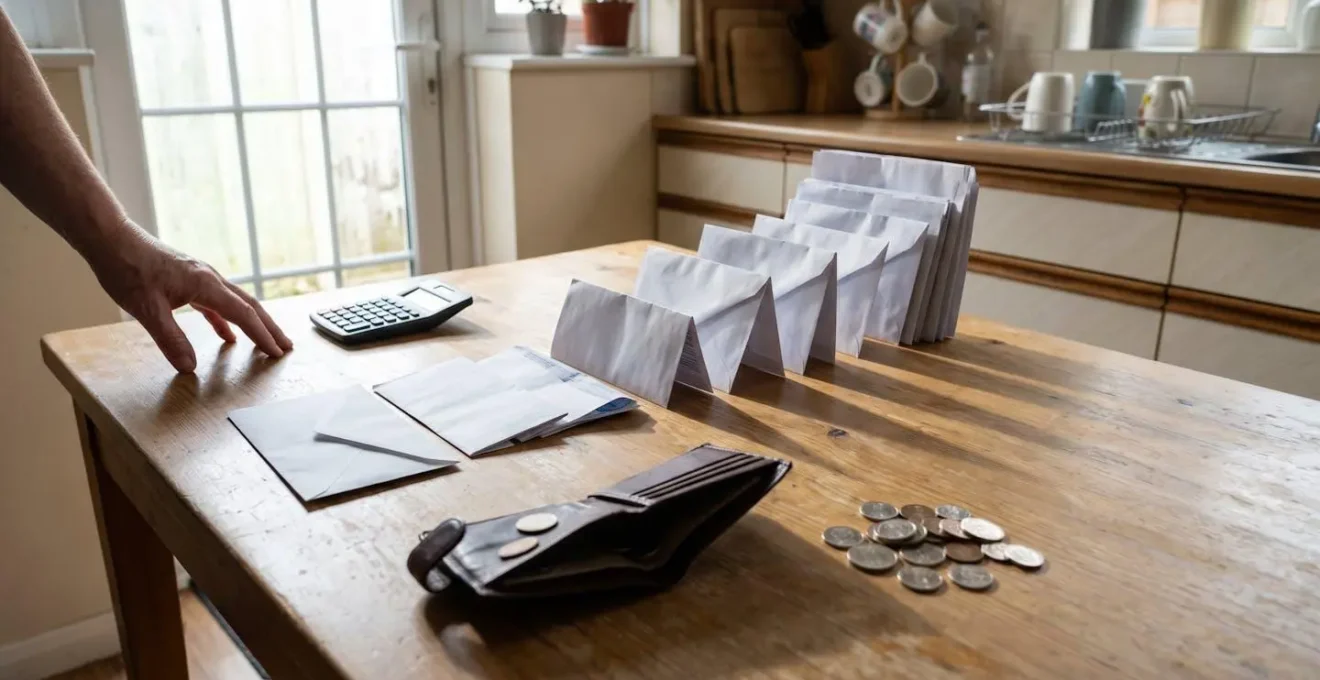
The scene above is the direct consequence of income underfunding. It is the quiet panic of bills piling up with no way to pay them. An income protection policy is the only tool designed specifically to prevent this scenario. It pays out a monthly, tax-free income that replaces a significant portion of your salary, allowing your family to meet its obligations and maintain its standard of living while you focus on recovery. Ignoring this risk is not a calculated gamble; it is an almost certain path to financial hardship for those you love most.
Why High-Net-Worth Individuals Need Umbrella Insurance Beyond Standard Home Policies?
For high-net-worth (HNW) individuals, the nature of financial risk extends far beyond the conventional concerns of life and health. Your assets, reputation, and public activities create a significantly larger liability footprint. Standard home and motor insurance policies, even high-end versions, come with liability limits that are wholly inadequate for the scale of claims HNW families can face. This is where Excess Liability or « Umbrella » insurance becomes not a luxury, but an essential component of wealth preservation.
These policies provide an additional layer of liability protection that sits on top of your existing home and auto policies. Where a standard policy might cap out at £2-5 million, an umbrella policy can extend that coverage to £10 million, £50 million, or more. It is designed to protect your accumulated wealth from a catastrophic lawsuit that could otherwise wipe it out. The risks are often hidden in plain sight, stemming from activities you might consider routine or even philanthropic.
Case Study: Director & Trustee Liability Exposure
An analysis by Risk Strategies’ Family Office practice highlights a critical vulnerability. Standard UK home insurance provides zero protection for liabilities arising from your role as a non-executive director, a school governor, or a charity trustee. A decision made in one of these capacities could lead to a personal lawsuit. Furthermore, claims from domestic staff for issues like wrongful termination or harassment can easily run into hundreds of thousands of pounds in damages. These scenarios are explicitly excluded from standard policies and require the specific, high-limit coverage of an excess liability policy to shield personal assets.
The scope of an umbrella policy is also broader. It can cover claims for defamation, libel, or slander—risks that are magnified in the age of social media. It provides a legal defence against opportunistic claims and covers damages awarded globally, not just in the UK. For HNW individuals, auditing your protection means looking beyond your health and assessing the multifaceted threats to your entire net worth.
Key Takeaways
- Your family’s true financial need, as calculated by the D.E.B.T.S. framework, is almost certainly far higher than any generic « rule of thumb » estimate.
- Employer « death in service » benefits create a dangerous illusion of security and should never be the foundation of your family’s protection plan.
- Underfunding your income is the most common and catastrophic mistake. The default state support is insufficient, making Income Protection the number one priority.
How to Shield Your Wealth From Ruinous UK Litigation and Compensation Claims?
Beyond insuring your life and health, a comprehensive protection audit for anyone with significant assets must address the growing threat of litigation. In an increasingly litigious society, your wealth can make you a target. Shielding your assets requires a deliberate, multi-layered strategy that goes beyond standard insurance policies. The goal is to create a defensive structure that not only covers potential claims but also acts as a powerful deterrent to opportunistic lawsuits.
A robust wealth-shielding strategy is built on three distinct layers of protection, working in concert to provide security at every level of risk. This structure ensures that smaller, more common disputes are handled efficiently without threatening your core assets, while catastrophic, « black swan » events are met with a formidable financial defence. It’s about having the right tool for every potential threat. This layered approach includes:
- The Foundational Layer: This is your first line of defence. It consists of high-quality, high-limit personal insurance policies. This means securing home and motor insurance with a minimum of £5 million in liability coverage, and obtaining comprehensive Directors’ & Officers’ (D&O) insurance for any board positions you hold.
- The Structural Layer: This involves legal and financial structuring. Working with specialist advisors, you can use UK-compliant trusts and other vehicles to legally separate personal assets from business and investment assets. This ring-fencing can place significant wealth beyond the reach of certain types of creditors and claimants.
- The Catastrophe Layer: This is your top-layer Excess Liability or Umbrella policy. As discussed, this provides multi-million-pound coverage for claims that exceed the limits of your foundational policies. Its existence alone can be a powerful deterrent, signalling to potential litigants that you have the resources for a protracted legal battle.
By implementing this three-layer strategy, you are not just insuring against risk; you are building a fortress around your wealth. It’s a proactive stance that demonstrates financial sophistication and provides peace of mind, knowing that a single unfortunate event cannot unravel a lifetime of hard work.
Your family’s security is too important to be left to assumptions or incomplete solutions. The next logical step is to move from theory to practice. To ensure every vulnerability is identified and addressed, you should seek a professional, confidential audit of your specific circumstances and existing policies.