The fundamental error most investors make is viewing debt as a burden to be minimized, rather than a tool to be precision-engineered.
- Effective leverage isn’t about the amount borrowed, but the architectural strength of your personal balance sheet and its resilience to UK-specific market stresses.
- Maximizing cash flow and managing liquidity via strategic debt structures (e.g., longer terms, interest-only) creates more wealth than accelerated repayment.
Recommendation: Shift from a debt-averse mindset to one of ‘liability engineering’, actively designing your debt to fuel asset acquisition and compound growth safely.
For the ambitious UK investor, the relationship with debt is the single most defining factor in the velocity of their wealth creation. Most are taught a simple, risk-averse narrative: debt is dangerous, a necessary evil to be paid down as quickly as possible. This approach is safe, but it is also slow, leaving decades of potential compound growth on the table. The common advice revolves around basic affordability and ensuring rental income covers the mortgage—essential, yet profoundly incomplete for anyone seeking to build a significant portfolio.
The truly sophisticated investor understands a counter-intuitive truth. Debt is not merely a financial instrument; it is a raw power source. Like any power source, it can be catastrophic if mishandled, but it can also be harnessed through meticulous engineering to achieve results that are impossible with unleveraged capital alone. This requires moving beyond the simplistic « good debt vs. bad debt » dichotomy and adopting the mindset of a financial architect. It involves designing a personal balance sheet where liabilities are not passive obligations but active, precision tools.
But what if the key wasn’t simply borrowing, but structuring that borrowing with systemic firewalls against market shocks? This is the principle of liability engineering. It’s an approach that focuses on creating a robust balance sheet architecture, one that can withstand interest rate hikes, void periods, and tax changes specific to the UK market. It’s about building a machine designed not just for growth, but for resilience.
This guide provides a technical framework for this exact purpose. We will deconstruct the mechanics of safe, effective leverage, moving from calculating your true borrowing capacity to structuring your portfolio for maximum capital velocity. We will explore how to measure liquidity, manage risk, and ultimately, transform bank capital from a potential liability into your most powerful asset for accelerating financial independence.
This article provides a comprehensive framework for structuring debt to accelerate wealth. Explore the detailed sections below to master each component of this strategic approach to leverage.
Summary: A Technical Guide to Engineering Debt for UK Investment Growth
- How to Calculate Your Safe Borrowing Limit for Property Investment?
- Why Using Lombard Loans Can Be Safer Than Selling Your Stock Portfolio?
- Good Debt vs Bad Debt: Which Accelerates Your Journey to Financial Independence?
- The Over-Leveraging Error That Bankrupts Ambitious Property Investors
- In What Sequence Should You Structure Multiple Buy-to-Let Mortgages?
- Current Ratio vs Quick Ratio: Which Best Measures Immediate Liquidity?
- Why Taking the Longest Mortgage Term Can Actually Make You Wealthier Over Time?
- How to Structure Your Mortgage to Build Property Wealth Faster in the UK Market?
How to Calculate Your Safe Borrowing Limit for Property Investment?
Calculating your safe borrowing limit is not about what a bank will offer you; it’s about what your personal balance sheet can withstand. Lenders, driven by competition, are increasingly pushing the boundaries. Indeed, recent data shows that nearly half of UK mortgage lending in 2024 has come from lenders offering aggressive 6x income multipliers. Relying solely on a lender’s affordability check is outsourcing your risk management to a sales function. The sophisticated investor builds their own dashboard.
The core of this calculation is a shift from income-based metrics to a holistic balance sheet architecture review. Your limit is determined by your portfolio’s resilience under duress, not just your current salary. This involves a rigorous stress test that simulates a « perfect storm » of negative events: interest rate spikes, extended vacancy periods, and a contraction in rental demand. Your true safe limit is the level of debt at which your portfolio remains cash-flow positive even in this worst-case scenario.
This requires quantifying your Personal Leverage Ratio (total liabilities / total assets) and understanding its sensitivity. For property investors, this must also factor in geographical and tenant-type concentration risk. A portfolio of ten properties in the same town, all rented to students, has a much lower effective borrowing limit than a geographically diversified portfolio with a mix of professional and family tenants, even if the headline LTV is the same. The goal is to define a limit that allows for growth while ensuring you never face a forced sale.
Your Personal Balance Sheet Stress Test: A 4-Point Audit
- Calculate your Personal Leverage Ratio by dividing total liabilities by total assets across all properties and other investments.
- Model the cash flow impact on your entire portfolio using the Bank of England’s recommended 5.5% stress test interest rate scenario, or higher.
- Assess your Portfolio Resilience Score based on the diversification of your assets by geography, property type, and tenant profile.
- Determine your optimal cash buffer by comparing the projected costs of a 3-6 month portfolio-wide void period against the lost opportunity cost of holding that cash.
Why Using Lombard Loans Can Be Safer Than Selling Your Stock Portfolio?
When liquidity is needed—for a property deposit, a business investment, or an unexpected expense—the default action for many investors is to sell a portion of their stock portfolio. This appears to be a « debt-free » solution, but it triggers multiple hidden costs and risks. Selling assets crystallises a Capital Gains Tax event, immediately eroding your capital. More critically, it permanently removes those assets from the market, sacrificing all future compound growth and dividends they would have generated. This is a one-way trip that can be incredibly expensive over the long term.
This is where a strategic use of leverage, specifically a Lombard loan or a Securities-Based Line of Credit (SBLOC), presents a technically superior and often safer alternative. Instead of selling your assets, you borrow against their value. This is not a sale, so it triggers no Capital Gains Tax. Your portfolio remains fully invested, continuing to benefit from market appreciation and compounding. The loan acts as a strategic liquidity bridge, allowing you to access cash without derailing your long-term investment strategy. The illustration below captures this fundamental difference in pathways.
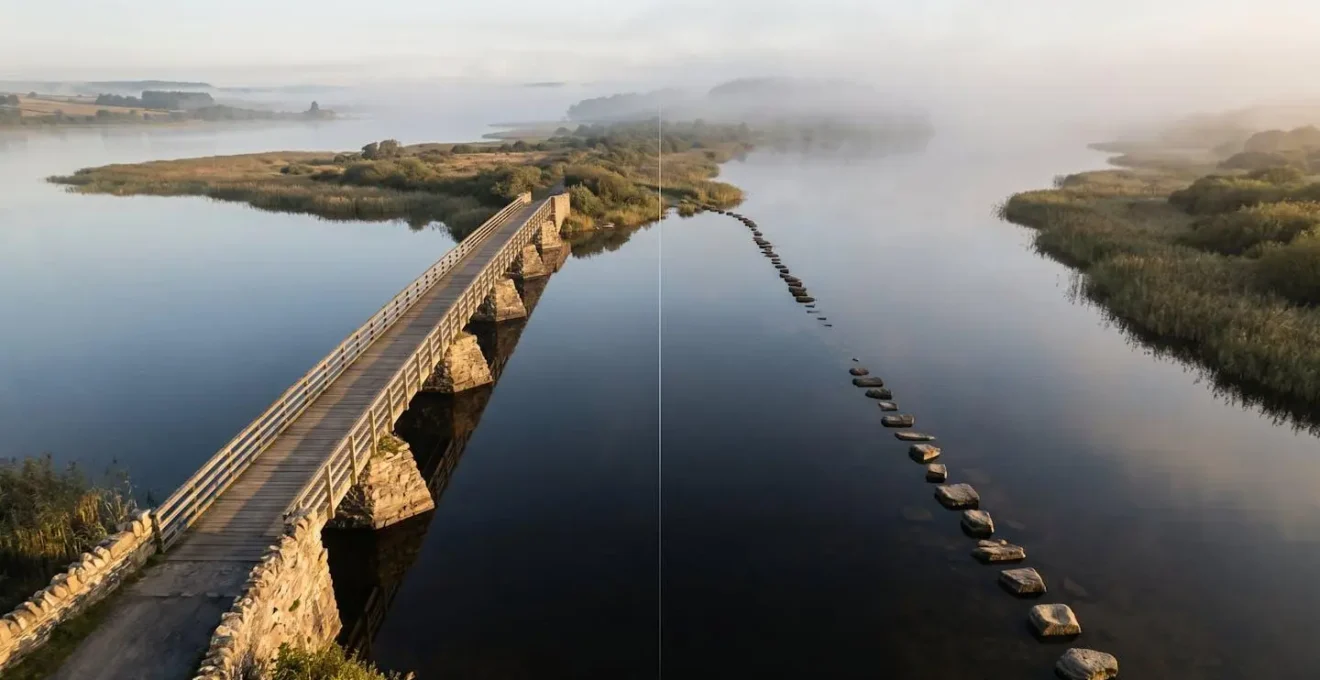
As you can see, one path preserves the core structure of your wealth, while the other liquidates it. According to an analysis by J.P. Morgan on paying with debt, this method is ideal for preserving long-term compounding. The key consideration is that these loans require a collateral buffer (you can’t borrow 100% of the value) and are subject to margin calls if the portfolio’s value drops significantly. However, for a well-diversified portfolio and a disciplined borrower, it is a powerful tool for managing liquidity without sacrificing growth. It transforms a static asset pool into a dynamic source of capital.
Good Debt vs Bad Debt: Which Accelerates Your Journey to Financial Independence?
The « good debt vs. bad debt » framework is a common starting point, but it lacks the quantitative rigour required by sophisticated investors. The simple definition—good debt buys appreciating assets, bad debt buys depreciating consumables—is true but insufficient. To truly accelerate wealth, we must move beyond this binary view and adopt a concept of a Debt Efficiency Score. This score evaluates debt not just on its purpose, but on its combined impact on your balance sheet, considering interest rate, tax benefits, and the underlying asset’s behaviour.
For example, a Buy-to-Let (BTL) mortgage held within a Limited Company (SPV) in the UK has a high Debt Efficiency Score. The interest is fully tax-deductible as a business expense, mitigating the impact of Section 24, and it finances an asset that (historically) appreciates and generates income. Conversely, a car loan has a destructive score: the interest rate is high, there are no tax benefits, and it finances a rapidly depreciating asset. Payday loans are an extreme example of wealth-destructive debt, with scores that are effectively catastrophic.
This quantitative approach allows for a more nuanced strategy. It’s not about avoiding all « bad » debt, but about understanding its cost and ensuring the overall ‘efficiency score’ of your personal balance sheet is strongly positive. As David Mook of U.S. Bank Private Wealth Management notes in an analysis on financial leverage:
You don’t want to be overleveraged in any way, shape or form, but leverage in moderation can be a really powerful tool
– David Mook, U.S. Bank Private Wealth Management
The following table provides a comparative framework for scoring different types of debt common in an investor’s portfolio, helping to visualise this efficiency spectrum.
| Debt Type | Typical Interest Rate | Tax Benefit | Asset Appreciation | Debt Efficiency Score |
|---|---|---|---|---|
| BTL Mortgage (Ltd Company) | 5-6% | Full deductibility | 3-5% annually | Positive (+2-4%) |
| Personal Mortgage | 4-5% | Limited | 3-5% annually | Neutral (0-1%) |
| Student Loan (Plan 2) | 7.3% | Income-contingent | N/A – Human capital | Variable |
| Car Loan | 7-9% | None | -15% annually | Negative (-20%+) |
| Payday Loan | 1500% APR | None | N/A | Destructive |
The Over-Leveraging Error That Bankrupts Ambitious Property Investors
Leverage is a double-edged sword, and its negative edge is lethally sharp. The most common and catastrophic error made by ambitious investors is mistaking a lender’s willingness to lend for a green light on risk. This is the over-leveraging trap: focusing solely on the magnified gains while underestimating the correlated risks. When the market turns, this single error can trigger a cascade failure across an entire portfolio. The primary mistake is not the level of debt itself, but a failure to build adequate systemic firewalls into the balance sheet architecture.
These firewalls are structural safeguards designed to contain financial fires. They include robust liquidity buffers, staggered mortgage term expiries, and, most importantly, a pre-mortem stress test. This involves imagining your portfolio has already failed and working backwards to identify the weak points. What happens if the Bank of England base rate hits 8%? How long can the portfolio survive a 100% vacancy rate? What is the cash flow impact if property values fall 20% and refinancing at the current LTV becomes impossible? The investor who cannot answer these questions with precise figures is driving blind.
Current market indicators show the importance of this diligence. While arrears remain low overall, Bank of England data reveals that mortgage stress indicators are flashing, with a significant portion of new lending occurring at high loan-to-income ratios. This creates a fragile environment where a small economic shock can have an outsized impact on highly leveraged investors. The image below captures the precariousness of a portfolio built without sufficient structural integrity.
Ultimately, the line between ambitious growth and reckless gambling is drawn by risk management. The investor who survives and thrives across cycles is the one who respects the destructive power of leverage and builds a fortress around their assets before expanding their territory. They understand that true wealth is not just about asset value, but about durability.
In What Sequence Should You Structure Multiple Buy-to-Let Mortgages?
As a property portfolio grows beyond a few assets, the structure of its financing becomes as important as the properties themselves. A common mistake is to treat each mortgage as a standalone transaction. The strategic investor, however, views the entire portfolio’s debt as a single, integrated system that needs to be engineered for resilience and flexibility. The key to this is a « mortgage ladder » or « tranche » strategy, which focuses on sequencing and diversifying the debt itself.
The primary goal is to avoid concentration risk in your refinancing schedule. Having multiple fixed-rate mortgages expiring in the same 12-month period creates a massive vulnerability. If that period coincides with a spike in interest rates or a tightening of lending criteria, you could be forced to refinance your entire portfolio on deeply unfavourable terms, potentially wiping out your cash flow. Successful portfolio investors mitigate this by staggering their fixed-rate expiry dates, typically across a 5-year cycle. This ensures that only a fraction of the portfolio (e.g., 20%) is exposed to the prevailing market rates in any given year.
This strategy is supported by market data. A Bank of England analysis of mortgage trends showed that a significant portion of mortgages are at high loan-to-income ratios, making borrowers sensitive to rate changes. The data also highlighted that savvy investors are actively using remortgaging not just to secure better rates, but to restructure their portfolios, with remortgages accounting for a substantial share of gross advances. By implementing a mortgage ladder, you create a systemic firewall. A rate shock in one year affects only one ‘rung’ of your ladder, giving you time and flexibility to adjust your strategy for the other tranches. This turns a potentially portfolio-wide crisis into a manageable, isolated event.
Current Ratio vs Quick Ratio: Which Best Measures Immediate Liquidity?
For a leveraged investor, liquidity is not just a metric; it is survival. While standard accounting ratios like the Current Ratio and Quick Ratio provide a baseline, they are often insufficient for the unique pressures of a property portfolio. The Current Ratio ((Cash + Liquid Investments) / Short-Term Obligations) can be misleadingly optimistic, as it may include assets like stocks within an ISA which, while liquid, you would be loath to sell under pressure. The Quick Ratio (Cash / Immediate Obligations) is more conservative but may not capture the full picture of an investor’s true cash buffer.
For a UK BTL investor, these traditional metrics must be adapted. A more powerful and practical set of ratios focuses on scenario-based survival. This is where you move from static balance sheet figures to dynamic cash flow modelling. For instance, the ‘Void Period Survival Ratio’ is arguably the single most important liquidity metric for a property investor. It answers a simple, brutal question: How many months can I continue to pay all my portfolio’s mortgages, insurance, and other costs if 100% of my tenants leave tomorrow? A healthy ratio here is typically 3-6 months.
Another UK-specific metric is ‘Offset Effectiveness’, which measures the portion of your mortgage debt being neutralised by cash held in an offset account. This represents a highly efficient form of liquidity, as the cash is simultaneously reducing interest payments while being instantly available. As highlighted in a Charles Schwab analysis on leveraging assets, the key is to adopt metrics that directly address the primary risks of the investment strategy. For BTL, that risk is vacancy. The table below, adapted for a leveraged UK investor, provides a more practical dashboard for measuring true liquidity.
This comparative analysis from wealth management experts helps reframe liquidity from a simple accounting exercise to a dynamic risk-management function.
| Ratio Type | Formula | Healthy Range | UK Context |
|---|---|---|---|
| Personal Current Ratio | (Cash + Liquid Investments) / 12-month obligations | 1.5 – 2.0 | Include ISA holdings as liquid |
| Personal Quick Ratio | Cash only / 3-month obligations | 1.0 – 1.3 | Emergency cash buffer |
| Void Period Survival | Cash buffer / Monthly portfolio costs if vacant | 3-6 months | Critical for BTL investors |
| Offset Effectiveness | Offset balance / Total mortgage debt | 10-20% | Reduces interest while maintaining liquidity |
Key takeaways
- Strategic borrowing is a form of financial engineering, not just taking on debt.
- Risk management for leverage in the UK must account for specific factors like Section 24 and variable lending criteria.
- Maximizing cash flow and liquidity through debt structure often provides superior long-term returns compared to rapid deleveraging.
Why Taking the Longest Mortgage Term Can Actually Make You Wealthier Over Time?
Conventional wisdom dictates that the shortest possible mortgage term is best, as it minimises the total interest paid. While mathematically true in isolation, this thinking is a classic example of optimising the wrong metric. For an investor, the primary goal is not to minimise interest paid to a bank; it is to maximise their own net worth. A longer mortgage term, paradoxically, is often a more powerful tool for achieving this objective due to its profound impact on cash flow and opportunity cost.
Consider two investors financing the same property. Investor A takes a 25-year term. Investor B takes a 35-year term. Investor B’s monthly payments will be significantly lower—often by 15-20%. While Investor B will pay more interest over the life of the loan if they see it to term, they gain a critical advantage: higher monthly cash flow. This surplus cash is not idle; it is capital that can be deployed. An analysis of this strategy shows that if this monthly difference is consistently invested into a diversified, low-cost investment vehicle like a global tracker fund within a tax-efficient wrapper like a UK ISA, the results are dramatic. Assuming historical market returns of 7-8% versus mortgage rates of 4-5%, the compound returns from the invested surplus can exceed the additional mortgage interest paid by a factor of two or three over the full term.
Furthermore, there is a second, more subtle benefit: inflation. A long-term mortgage is a contract to repay a fixed nominal sum with future, less valuable money. In an inflationary environment, the real value of your debt is constantly eroding, while the nominal value of your asset (the property) is likely to rise. Taking a longer term maximises the time over which this powerful effect can work in your favour. The lower monthly payment enhances liquidity, reduces personal financial stress, and frees up capital for higher-return investments, creating superior capital velocity. For the strategic investor, a mortgage is a tool, and a longer term simply keeps that tool cheap and flexible for longer.
How to Structure Your Mortgage to Build Property Wealth Faster in the UK Market?
Building property wealth at an accelerated pace in the UK is a function of maximising capital velocity—the speed at which you can reinvest your equity and cash flow. The structure of your mortgage finance is the primary engine for this velocity. A poorly structured mortgage traps equity and strangles cash flow, while a well-engineered one acts as a perpetual motion machine for portfolio growth. Several key strategies are central to this engineering process for the UK market.
First, the use of interest-only (IO) mortgages for BTL properties is a cornerstone strategy. By only servicing the interest, monthly outgoings are dramatically reduced, maximising net cash flow. This surplus cash can then be accumulated for the deposit on the next property, allowing for much faster expansion than a capital repayment model would permit. This strategy, of course, relies on the asset’s capital appreciation to repay the principal, making property selection and a long-term view critical.
Second, the post-Section 24 tax environment makes structuring essential. Holding properties within a Limited Company SPV is now standard practice for higher-rate taxpayers, as it allows for 100% of the mortgage interest to be treated as a deductible business expense. This single structural choice can have a profound impact on profitability and the capital available for reinvestment. Combining this with other tools like offset mortgages to maintain liquidity while reducing interest costs, and using short-term bridging finance for « value-add » projects (e.g., renovations) before refinancing onto a standard BTL product, creates a powerful toolkit. The optimal structure is typically a portfolio LTV of around 75%, balancing aggressive leverage for growth with a safety buffer against market downturns.
To implement this framework effectively, the next logical step is to conduct a full audit of your current balance sheet and debt structure against these principles to identify opportunities for optimisation and enhanced resilience.
Frequently Asked Questions on Strategic Leverage for Property Investment
Should I use different lenders or consolidate with one for my BTL portfolio?
Diversifying across 2-3 lenders reduces concentration risk while maintaining manageable relationships. UK lenders’ criteria vary significantly, particularly for portfolio landlords, and relying on a single lender exposes you to the risk of them changing their lending policy, which could halt your portfolio’s growth.
How do I manage credit file impact when expanding my portfolio?
Sequence your mortgage applications 3-6 months apart to allow your credit file to stabilise between searches. It is highly advisable to use specialist mortgage brokers who understand portfolio lending; they can perform ‘soft searches’ and have access to lenders who are more accommodating to professional investors. Regularly monitor all three UK credit agencies (Experian, Equifax, TransUnion) to ensure accuracy.
What’s the optimal strategy: BRRR or Portfolio Blanket Loan?
The optimal strategy depends on your goals and management capacity. The BRRR (Buy, Refurbish, Rent, Refinance) method offers maximum capital velocity and recycling but requires intensive, active management for each project. A portfolio blanket loan provides simplicity by consolidating debt under one facility but offers less flexibility for individual properties. Most successful large-scale investors use a hybrid approach: employing the BRRR strategy for growth phases and then periodically consolidating tranches of stabilised assets into portfolio loans for easier management.