The greatest threat to your family’s inheritance is not an external creditor; it is an improperly structured trust managed by a well-intentioned but legally unprepared family member.
- A Discretionary Trust offers a formidable legal shield against creditors, divorce, and generational mismanagement, but only when administered with professional diligence.
- Appointing amateur trustees, while seemingly cost-effective, exposes them to significant personal liability and can lead to the very wealth destruction the trust was designed to prevent.
Recommendation: The selection of a trustee should be treated as the most critical strategic decision in estate planning, prioritising fiduciary expertise and impartiality over familial connection.
For high-net-worth parents, the ambition is not merely to accumulate wealth, but to ensure it serves as a foundation for future generations. The challenge lies in transferring this wealth without exposing it to the risks of creditors, contentious divorces, or the financial immaturity of beneficiaries. Many turn to trust structures as a solution, having heard of their protective qualities. This is a sound starting point, but it often overlooks the most critical point of failure.
The common discourse focuses on the legal drafting of the trust deed. However, the true resilience of a trust does not lie solely in its clauses, but in the hands of those who govern it. What if the very structure you create to protect your wealth becomes the source of its destruction? This guide moves beyond the basics of trust formation to address the critical, often-underestimated human element: the trustee. We will demonstrate that the legal fortress you build is only as strong as the gatekeeper you appoint.
By dissecting the immense responsibilities and personal liabilities of a trustee, we will show why the seemingly simple choice of appointing a family member can be a catastrophic error. This analysis will equip you to make informed decisions, not just about which structure to use, but, more importantly, who should manage it to truly secure your family’s legacy.
Summary: A Strategic Guide to UK Trusts and Asset Protection
- How to Set Up a Discretionary Trust to Protect Your Children’s Inheritance?
- Why Appointing a Family Member as Trustee Often Leads to Legal Disasters?
- Bare Trusts vs Discretionary Trusts: Which Offers Better Asset Protection?
- The Fiduciary Breach That Holds Amateur Trustees Personally Liable for Losses
- When to Hand Over Trust Management to a Certified Corporate Fiduciary?
- How to Legally Reduce a 40% Inheritance Tax Bill Using Annual Gift Allowances?
- How to Set Up a Family Investment Company to Bypass Standard Inheritance Rules?
- How to Use a Family Investment Company to Cascade Wealth Tax-Free in the UK?
How to Set Up a Discretionary Trust to Protect Your Children’s Inheritance?
A Discretionary Trust is a powerful instrument for wealth protection, primarily because no single beneficiary has an absolute right to the assets. Instead, trustees hold the assets and have discretion over how and when distributions are made to a defined class of beneficiaries. This separation is the cornerstone of its protective power against creditors or divorce settlements targeting a beneficiary.
However, establishing this structure requires absolute legal precision. The process begins with a meticulously drafted trust deed, which must clearly state the intention to create a trust, define the property within it, and specify the class of potential beneficiaries (e.g., « my children and their future descendants »). Alongside this legal document, a non-binding « letter of wishes » is created to guide the trustees on how you would like them to exercise their discretion, providing a moral compass for their decisions.
The financial implications are immediate and significant. Under current UK rules, placing assets into a Discretionary Trust can trigger a 20% immediate tax charge on assets exceeding the £325,000 nil-rate band. Furthermore, the trust must be registered with HMRC’s Trust Registration Service within 90 days. These complexities are not procedural hurdles; they are tripwires for the unwary. A well-structured trust is highly cost-effective when compared to potential 40% Inheritance Tax (IHT) liabilities or weekly care home fees that can exceed £1,200, but its setup is a professional undertaking, not a DIY project.
This initial setup is merely the first step; the true challenge lies in its ongoing governance, which determines whether the trust remains a fortress or becomes a liability.
Why Appointing a Family Member as Trustee Often Leads to Legal Disasters?
The temptation to appoint a trusted family member—a sibling, a spouse, or an adult child—as a trustee is understandable. It seems personal, cost-free, and straightforward. This is what we call the « Amateur Trustee Trap, » a well-intentioned decision that routinely culminates in legal, financial, and familial disaster. The role of a trustee is not an honorary title; it is a demanding fiduciary position fraught with personal liability.
An amateur trustee is often unaware of the stringent legal duties they are undertaking. They must act impartially, manage complex tax filings, and make prudent investment decisions according to a higher standard than they would for their own money. Failure to meet these obligations can have severe consequences. For example, trustees face penalties exceeding £5,000 for failing to file required IHT100 forms with HMRC, a common oversight for those not versed in trust administration.
The most significant risk, however, is the inherent conflict of interest, especially if the trustee is also a beneficiary. As Royal London for Advisers points out, this creates a situation ripe for dispute. The firm’s guidance highlights a critical legal principle:
The trustees using their power of discretion to pay to themselves creates a conflict of interest, as the children are benefiting personally from their role as trustee.
– Royal London for Advisers, Can a Trustee payout to themselves under a discretionary trust?
This conflict can lead to unequal distributions, resentment among siblings, and costly litigation that drains the very assets the trust was meant to protect. The emotional toll of pitting family members against each other in a legal battle often causes irreparable damage.
Ultimately, the perceived savings of not hiring a professional are dwarfed by the potential for legal fees, tax penalties, and the erosion of family harmony.
Bare Trusts vs Discretionary Trusts: Which Offers Better Asset Protection?
Not all trusts are created equal, and the distinction between a Bare Trust and a Discretionary Trust is a stark illustration of this principle. A Bare Trust is the simplest form: the trustee holds the assets, but the beneficiary has an absolute and immediate right to them (and the income they generate) upon reaching the age of 18 (in England and Wales). From a legal perspective, the assets belong to the beneficiary. This structure offers virtually no asset protection. If the beneficiary gets divorced, faces creditors, or is financially irresponsible, the assets in the Bare Trust are fully exposed and will be treated as their personal property.
A Discretionary Trust, by contrast, provides a robust « discretionary barrier. » The trustees are the legal owners of the assets, and no beneficiary has an automatic entitlement. This is the key to its superior protection. The assets are not considered part of a beneficiary’s estate for the purposes of a divorce settlement or creditor claim. The following comparison highlights the fundamental differences in their protective capabilities, based on a detailed analysis of trust structures.
| Protection Aspect | Bare Trust | Discretionary Trust |
|---|---|---|
| Creditor Protection | None – Assets belong directly to beneficiary | Strong – Trustees are legal owners |
| Divorce Protection | None – Counted as beneficiary’s assets | Protected – Not matrimonial property |
| Beneficiary Control | Full control at age 18 | No automatic entitlement |
| Tax Treatment | Taxed as beneficiary’s income | 45% trust rate on income |
| Flexibility | No flexibility – fixed beneficiary | Complete trustee discretion |
To illustrate this difference more starkly, one can think of a Bare Trust as a transparent glass box—the contents are visible and easily accessed by outsiders. A Discretionary Trust is more akin to a fortified limestone vault, where the gatekeeper holds the only key and decides who gets access and when.
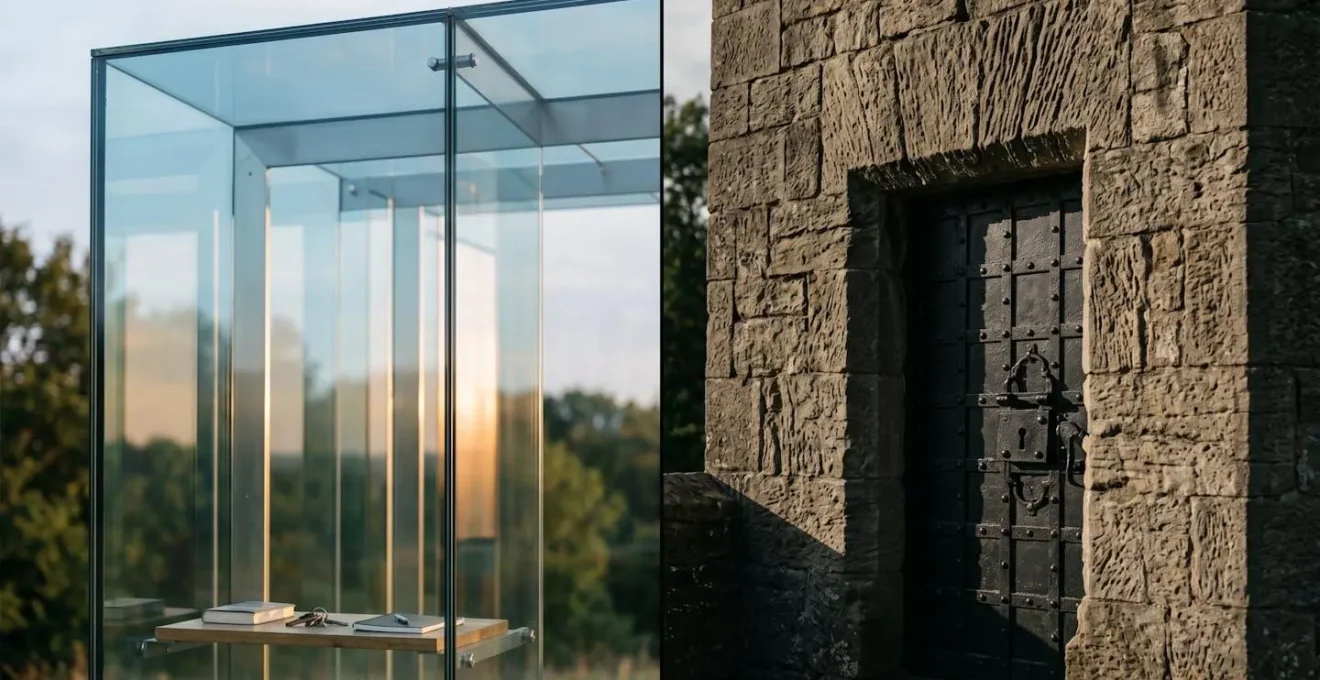
While a Bare Trust may be suitable for simple, low-risk gifts, for the purpose of long-term, multi-generational wealth preservation and protection from life’s uncertainties, the Discretionary Trust is unequivocally the superior instrument.
However, the strength of this fortress depends entirely on the integrity and competence of the person holding the key—the trustee.
The Fiduciary Breach That Holds Amateur Trustees Personally Liable for Losses
The term « fiduciary duty » is not a vague ethical guideline; it is a strict legal standard that holds a trustee personally responsible for the trust’s assets. A breach of this duty, even if unintentional, can result in the trustee being forced to cover any financial losses from their own pocket. This is a risk that most amateur trustees are dangerously unaware they are accepting. The core duties include acting with undivided loyalty to the beneficiaries, avoiding any conflicts of interest, and managing the trust’s assets with prudence.
A common fiduciary breach occurs in investment management. The « prudent investor rule » legally requires trustees to diversify trust assets and manage risk, a standard often far more rigorous than how they might manage their own portfolio. A well-meaning family member who invests the trust’s capital in a single « sure thing » that fails could be held personally liable for the entire loss. A crucial point often missed is that if you find yourself in the difficult position of being a trustee, rectifying a bad situation is not straightforward. The case of Seymour v Ragley Trust Company & Ors demonstrated that the legal threshold for removing a trustee is exceptionally high. A mere breakdown in relations or disagreement over decisions is often insufficient, meaning a poor choice of trustee can become a long-term problem.
To avoid such catastrophic outcomes, a trustee must adhere to a strict procedural and ethical code. This is not a matter of intuition; it is a matter of law.
Your Action Plan: Key Trustee Legal Duties to Avoid Personal Liability
- Act impartially: Treat all beneficiaries fairly and in accordance with trust terms, not favoring personal interests or one beneficiary over another.
- Maintain transparency: Keep detailed records of all decisions and communications, and seek independent advice for significant actions to prove diligence.
- Follow the prudent investor rule: The legal standard is not what you would do with your own money. You must diversify trust assets appropriately and justify your investment strategy.
- Document distribution justifications: Meticulously record the reasoning for any and all distributions, especially if they are unequal, to defend against future legal challenges.
- Avoid conflicts of interest: Ensure your personal interests never conflict with your role as trustee. If a conflict is unavoidable, it may require court approval to proceed.
This legal minefield is precisely why the detached, expert judgment of a professional fiduciary is often the most prudent choice for significant trusts.
When to Hand Over Trust Management to a Certified Corporate Fiduciary?
The decision to appoint a corporate fiduciary, or professional trustee, is a strategic one, moving the trust from a family affair to a professionally managed entity. While there is a cost involved, it should be viewed as an insurance premium against legal breaches, tax errors, and family conflict. A corporate fiduciary brings impartiality, expertise, and, crucially, institutional continuity—ensuring the trust is managed consistently for decades, beyond the lifespan of any individual.
Certain red flags should signal that the complexity and risk of the trust have outgrown the capabilities of an amateur trustee. The need for a professional becomes acute when the trust holds significant illiquid assets, such as business interests, which require sophisticated valuation and management. Likewise, the presence of cross-border assets introduces a maze of international tax laws that a family member is simply not equipped to navigate. Perhaps the most compelling reason is the existence of contentious family dynamics; a corporate trustee acts as an impartial buffer, making decisions based on the trust deed and letter of wishes, not emotion or personal allegiance.
Generally, when a trust’s value exceeds £1 million, the complexity, compliance burdens, and potential liabilities justify the management fees of a professional. Their involvement transforms the trust from a potential source of family friction into a secure, professionally administered vehicle for wealth preservation. They are not beholden to any single beneficiary and are duty-bound to act in the best interest of the trust as a whole, providing a level of protection that no family member, however well-intentioned, can truly offer.
This transition marks the ultimate step in securing a trust, ensuring it fulfills its purpose of protecting and growing wealth across generations without destroying family relationships.
How to Legally Reduce a 40% Inheritance Tax Bill Using Annual Gift Allowances?
Inheritance Tax (IHT) in the UK is a significant threat to generational wealth transfer, levied at a flat rate of 40% on assets above the available thresholds. The primary threshold, the nil-rate band, has been a major driver of IHT bills because the inheritance tax nil rate band has been frozen at £325,000 since 2009 and is set to remain at that level until at least April 2028. This fiscal drag means more and more estates are being caught by the tax.
One of the most effective strategies for mitigating IHT is to reduce the value of your estate during your lifetime through gifting. While outright gifts to individuals are simple, they offer no asset protection for the recipient. Gifting into a Discretionary Trust provides a powerful alternative, combining IHT reduction with robust control and protection. The key mechanism is the « seven-year rule. » When you place assets into a Discretionary Trust, it is considered a « Chargeable Lifetime Transfer. » If you survive for seven years after making this gift, its value falls completely outside your estate for IHT purposes, effectively shielding it from the 40% tax charge on death.
This can be combined with various annual allowances. For instance, every individual has a £3,000 annual exemption for gifts. You can also make regular gifts out of your surplus income, which are immediately exempt from IHT provided they are part of a regular pattern and do not diminish your standard of living. By strategically using a combination of these allowances and larger chargeable transfers into a trust, it is possible to systematically move significant wealth out of your estate over time, substantially reducing the final IHT bill while ensuring the assets are managed and protected for your beneficiaries.
This proactive approach to estate planning is far superior to leaving the full value of an estate to be taxed at the highest rate.
How to Set Up a Family Investment Company to Bypass Standard Inheritance Rules?
While trusts are a primary tool for estate planning, a Family Investment Company (FIC) offers a compelling alternative, particularly for families who wish to retain a greater degree of control over assets. An FIC is a private company whose shareholders are family members. It allows parents to pass value to the next generation in a controlled, tax-efficient manner without relinquishing management of the underlying investments.
The structure is typically established by creating different classes of shares. Parents might hold « A » shares, which carry all the voting rights, making them the sole directors with complete control over investment decisions. Children and grandchildren are then gifted or subscribe for « B » shares, which have no voting rights but are entitled to dividends and capital growth. This structure allows wealth to grow in the hands of the younger generation while the parents retain absolute control over the company’s strategy.
Unlike a Discretionary Trust, where you must cede control to trustees, an FIC allows the parents to remain at the helm. Funding is also flexible; parents can loan money to the FIC, which can be repaid tax-free in the future, rather than subscribing for shares. For IHT purposes, the growth in value of the children’s « B » shares occurs outside the parents’ estate. For enhanced asset protection, the children’s shares can even be held within a separate Discretionary Trust, creating a hybrid structure that combines the control of an FIC with the protective barrier of a trust, which can last for up to 125 years.
This sophisticated structure provides a powerful mechanism for cascading wealth, but its suitability must be weighed against the relative simplicity and creditor protection of a traditional trust.
Key Takeaways
- The ultimate strength of a trust lies not in its legal text but in the impartiality and expertise of its trustees.
- A Discretionary Trust offers unparalleled asset protection against creditors and divorce, a feat a Bare Trust cannot achieve.
- The choice of trustee is the single most critical decision, with the « Amateur Trustee Trap » being the most common and costly mistake in estate planning.
How to Use a Family Investment Company to Cascade Wealth Tax-Free in the UK?
The strategic choice between a Family Investment Company (FIC) and a Discretionary Trust is a matter of balancing control, tax efficiency, and asset protection. There is no one-size-fits-all answer; the optimal choice depends entirely on the family’s specific objectives and risk tolerance. An FIC offers unparalleled control, while a trust provides a superior shield against external threats.
Taxation is a significant differentiator. An FIC’s income and gains are subject to corporation tax (currently 19-25%), and tax is paid again by shareholders when funds are extracted as dividends. A Discretionary Trust, on the other hand, faces a high 45% tax rate on most income, designed to encourage distribution rather than accumulation. Crucially, a gift into an FIC does not typically trigger the 20% upfront IHT charge that applies to trusts funded above the nil-rate band, making it more attractive for large initial transfers.
However, this tax and control advantage comes at the cost of weaker creditor protection. The assets of an FIC belong to the company, and while shareholders have limited liability, the company itself can be pursued by creditors. A trust, by contrast, severs the legal link between the beneficiary and the assets, offering a much stronger defence. The following table provides a high-level comparison of these two powerful structures.
| Feature | Family Investment Company | Discretionary Trust |
|---|---|---|
| Corporation Tax | 19-25% on income/gains | N/A – different tax regime |
| Income Tax Rate | Dividend tax on extraction | 45% trust rate |
| IHT Entry Charge | None if structured correctly | 20% over £325,000 |
| Creditor Protection | Weaker – company assets exposed | Strong – trust separation |
| Director/Trustee Control | Direct control as directors | Must cede control to trustees |
| Exit Strategy Complexity | CGT on wind-up/sale | Exit charges may apply |
Your family’s financial future is too important to leave to chance or good intentions. To determine the most robust and tax-efficient structure for your unique circumstances, the next logical step is to seek a professional fiduciary assessment.